
What is a Nondeductible IRA?
A nondeductible IRA is a traditional IRA where the IRA owner made contributions on an after-tax basis because she was not eligible to take IRA deductions because of high income earnings and as a result did not claim deduction when filing the personal Form 1040 tax return. Lastly, nondeductible IRA contributions are tracked by completing Form 8606 and submitting it to the IRS when Form 1040 is filed.
The conversion of IRAs including nondeductible IRA funds (after-tax) to a Roth IRA is known as Roth IRA conversion which is a reportable event (IRC Sec. 408A(d(93)(C). For more information on the Roth IRA conversion requirements see also (Treas. Reg. 1.408A-4, Q&A 4).
Taxation of the Roth IRA Conversion
The rules require all of the individual’s IRAs treated as one when calculating the taxes due, if any, on the conversion. While the IRA conversion is reportable it is generally not taxable if just the non-deductible IRA basis is converted, with the gains directly rolled over to a pretax 401k including a solo 401k. For more on the strategy of first isolating non-deductible IRA funds using a solo 401k for the self-employed, visit here.
Important Note:
If your goal is to isolate your nondeductible IRA funds, make sure to first process a direct rollover of the gains in the nondeductible IRA as well as of your other IRAs including SEP IRAs and SIMPLE IRAs to a 401k or a solo 401k if your are eligible before you process the conversion of the nondeductible IRA funds to the Roth IRA so that none of the conversion will be taxable.
Reporting
Roth IRA conversions are reported on Form 1099-R and 5498. Roth IRA conversions are also reported on Form 8606. When the IRA is directly converted to the Roth IRA, the funds are directly deposited to the Roth IRA which can be done internally if both IRAs (i.e., the IRA and the Roth IRA) are held at the same financial institution; if not, then a check is made payable in the name of the receiving financial institution where the Roth is opened. One advantage of doing a direct conversion is that the 60-day and one-per 12 month rollover rule doesn’t apply.
Form 1099-R Reporting
A Form 1099-R is used to report the direct conversion of IRA funds to a Roth IRA by the financial organization holding the IRA using a code 2, Early distribution, exception applies, in box 7 if the IRA owner is under age 59 1/2. If the IRA owner is at least 59 1/2, Code 7 applies.
https://www.irs.gov/pub/irs-pdf/i1099r.pdf


https://www.irs.gov/forms-pubs/about-form-1099-r

Form 5498 Reporting
The financial organization that holds the Roth IRA and receives the conversion reports the amount converted in box 3, Roth IRA conversion amount, of Form 5498.

Reporting the Roth Conversion of Form 8606
See the following: https://www.irs.gov/forms-pubs/about-form-8606
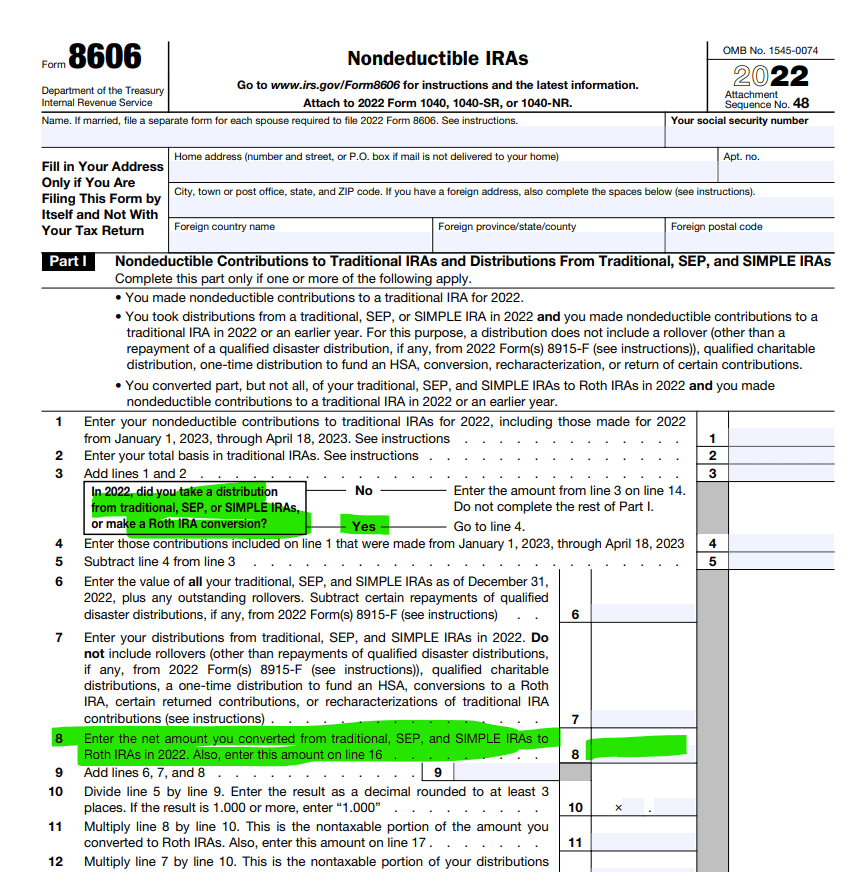
Form 8606 Completion Continued
Part II—Conversions From Traditional, SEP, or SIMPLE IRAs to Roth IRAs
Complete Part II if you converted part or all of your traditional, SEP, or SIMPLE IRAs to a Roth IRA in 2022.
Line 16
If you didn’t complete line 8, see the instructions for that line. Then, enter on line 16 the amount you would have entered on line 8 had you completed it.
Line 17
If you didn’t complete line 11, enter on line 17 the amount from line 2 (or the amount you would have entered on line 2 if you had completed that line) plus any contributions included on line 1 that you made before the conversion.
Line 18
If your entry on line 18 is zero or less, don’t include the result on 2022 Form 1040, 1040-SR, or 1040-NR, line 4b. Include the full amount of the distribution on 2022 Form 1040, 1040-SR, or 1040-NR, line 4a.

If the IRAs (The Roth IRA and the Nondeductible IRA) Are at Same Financial Organization
To make the Roth IRA conversion easier on you, consider redesignating the IRA as a Roth IRA if you process the conversion with the same financial organization. See (Treas. Reg. 1.408A-2, Q&A 2, and 1.408A-4, Q&A 1). This method is ideal if you don’t already have a Roth IRA. The same Form 1099-R and Form 5498 reporting still applies, of course.