Solo 401(k) for Partnerships: 2026 K-1 income needed for a $72,000 max

Partnership Playbook: 2026 Solo 401(k) Income Needed to Maximize Contributions

Direct answer

Solo 401(k) for partnerships needs at least $252,317.72 of Schedule K-1 Box 14 Code A income to fund $72,000 of pre-tax contributions in 2026. A $72,000 voluntary after-tax contribution, the first step of a Mega Backdoor Roth, needs only $77,473.32. Both figures apply to partners under age 50 and are calculated after subtracting one-half of self-employment tax.

Key takeaways

  • The 2026 Solo 401(k) overall limit is $72,000, and an $8,000 catch-up contribution (or $11,250 super catch-up at ages 60 to 63) raises it to $80,000 or $83,250.
  • Solo 401(k) for partnerships starts from self-employment compensation, which equals Schedule K-1 Box 14 Code A income minus one-half of self-employment tax.
  • A partner under age 50 needs $252,317.72 of Box 14 Code A income to make $72,000 of pre-tax contributions: a $24,500 employee deferral plus a $47,500 employer contribution.
  • A partner whose day-job plan already uses the $24,500 employee limit needs $376,480.35 of K-1 income to make a $72,000 pre-tax employer contribution.
  • A $72,000 voluntary after-tax contribution for a Mega Backdoor Roth needs only $77,473.32 of K-1 income, because it is not limited to a percentage of pay.
  • A partner age 50 to 59 or 64+ needs $86,081.46 of K-1 income to make $80,000 of Mega Backdoor Roth plus Roth catch-up contributions in 2026.
  • A partner age 60 to 63 needs $89,578.52 of K-1 income to make $83,250 of Mega Backdoor Roth plus Roth super catch-up contributions in 2026.
  • The SECURE 2.0 Roth catch-up mandate applies to W-2 FICA wages above $150,000 for 2025, so partners reporting K-1 income are not forced into Roth catch-ups.

Solo 401(k) for partnerships: My Solo 401k Financial live webinar, “Partnership Playbook: 2026 Solo 401(k) Income Needed to Maximize Contributions,” held .

How much partnership income do you need to max out a Solo 401(k) in 2026?

Solo 401(k) for partnerships has no single income threshold, because the K-1 income a partner needs depends on which contribution type the partner wants to maximize.

The table lists the minimum Schedule K-1 Box 14 Code A income for each 2026 goal, as calculated in the webinar.

Minimum Schedule K-1 Box 14 Code A income needed for each 2026 Solo 401(k) contribution goal
Contribution goal Age at end of 2026 Contribution amount Self-employment compensation needed K-1 Box 14 Code A income needed
Pre-tax employee + employer Under 50 $72,000 ($24,500 employee + $47,500 employer) $237,500 $252,317.72
Pre-tax employee + employer + catch-up 50–59 or 64+ $80,000 ($32,500 employee + $47,500 employer) $237,500 $252,317.72
Pre-tax employee + employer + super catch-up 60–63 $83,250 ($35,750 employee + $47,500 employer) $237,500 $252,317.72
Pre-tax employer contribution only Employee limit already used in another plan $72,000 (employer) $360,000 $376,480.35
Mega backdoor Roth (voluntary after-tax) Under 50 $72,000 $72,000 $77,473.32
Mega backdoor Roth + Roth catch-up 50–59 or 64+ $80,000 ($72,000 after-tax + $8,000 catch-up) $80,000 $86,081.46
Mega backdoor Roth + Roth super catch-up 60–63 $83,250 ($72,000 after-tax + $11,250 super catch-up) $83,250 $89,578.52

What are the 2026 Solo 401(k) contribution limits?

Solo 401(k) for partnerships uses four 2026 limits: the employee limit, the catch-up amounts, the 20% employer limit, and the overall limit.

A Solo 401(k) holds three contribution buckets. The employee bucket and the employer bucket are the traditional two. The third bucket is the voluntary after-tax contribution, which supports Mega Backdoor Roth Solo 401(k) contributions.

2026 Solo 401(k) contribution limits (current law)
Limit 2026 amount Who it applies to
Employee deferral limit $24,500 All participants; shared across every plan a person joins
Catch-up contribution $8,000 Age 50 or older at the end of 2026
Super catch-up contribution $11,250 instead of $8,000 Age 60 to 63 at the end of 2026
Employer contribution limit 20% of self-employment compensation Partners funding a Solo 401(k) from Schedule K-1 income
Overall limit $72,000 Employee, employer, and voluntary after-tax contributions combined (plus any 403(b) contributions)
Overall limit with catch-up $80,000 or $83,250 $80,000 at age 50–59 or 64+; $83,250 at age 60–63

How do you calculate self-employment compensation from Schedule K-1 Box 14 Code A?

Solo 401(k) for partnerships measures every limit against self-employment compensation, which is Box 14 Code A income minus one-half of self-employment tax.

The solo 401(k) exists so a self-employed person can save earned self-employment income. A participant cannot save more than the participant earns.

What counts as Solo 401(k) income for a partnership?

  • Earned self-employment income reported in Box 14 Code A of Schedule K-1.
  • Guaranteed payments for services, when they are reported in Box 14 with the right code.
  • Income of active general partners and managing LLC members.

What does not count?

  • W-2 wages from a day job.
  • Investment income, such as Schedule E rental income.
  • Owner income that is not earned self-employment income.
  • Distributive shares of limited partners under IRC § 1402(a)(13), and income of capital-only partners who perform no services.
  • Entity gross revenue before business expenses.

How much K-1 income does a partner need for $72,000 of pre-tax contributions?

Solo 401(k) for partnerships requires $252,317.72 of Box 14 Code A income for a partner under age 50 to make $72,000 of pre-tax employee and employer contributions.

“Well, the magic number is right here on the screen. $252,317.72. Because remember, you got to run that pre-calculation … You reduce that amount by one half of self-employment tax.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial
(13:30 in the webinar)

After one-half of self-employment tax, that income leaves $237,500 of self-employment compensation. The partner contributes 100% of compensation up to the $24,500 employee limit. The employer contribution is 20% of $237,500, which is $47,500. Together the two total $72,000.

Does the K-1 income change with catch-up contributions?

Solo 401(k) for partnerships needs the same $252,317.72 at every age for the pre-tax scenario. The employee deferral rises to $32,500 with the $8,000 catch-up, and the employer contribution stays at $47,500. The total becomes $80,000. At ages 60 to 63, the $11,250 super catch-up lifts the total to $83,250.

Does the Roth catch-up mandate apply to partners using a Solo 401(k)?

Solo 401(k) for partnerships does not force Roth catch-up contributions unless the partner receives W-2 wages from the sponsoring business.

SECURE 2.0 requires participants with W-2 FICA wages above $150,000 for 2025 to make catch-up contributions as Roth contributions. Partners receive and report earned self-employment income on Schedule K-1 Box 14, not W-2 wages.

“But what’s important to understand is that you have to have W-2 wages from the business that sponsors the solo 401k to be forced to make those catch-up contributions as Roth contributions.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial
(16:57 in the webinar)

Partners therefore keep the option to make catch-up contributions pre-tax. Roth catch-up contributions remain allowed under the My Solo 401k Financial plan but are not mandated. A partner’s separate W-2 job with an unrelated employer is tested under that employer’s plan only.

How much partnership income is needed if a day-job 401(k) already uses the employee limit?

Solo 401(k) for partnerships limits employee contributions across every plan a partner joins, so a maxed day-job 401(k) leaves only the employer bucket for pre-tax savings.

The employer contribution limit is 20% of self-employment compensation. A $72,000 employer contribution therefore requires $360,000 of compensation. Reaching $360,000 after one-half of self-employment tax requires at least $376,480.35 in Box 14 Code A.

“… their employer contribution limit is 20% of their self-employment compensation. So, effectively, if they want to make a $72,000 employer pre-tax contribution, they would need $360,000 of self-employment compensation.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial
(18:53 in the webinar)

Important: Contributions to a 403(b), whether made by the participant or an employer, count toward the same $72,000 overall limit as Solo 401(k) contributions. Other day-job plans do not reduce the employer or voluntary after-tax limits, according to the webinar.

How much K-1 income does a partner need for Mega Backdoor Roth contributions?

Solo 401(k) for partnerships supports a $72,000 Mega Backdoor Roth contribution with $77,473.32 of K-1 income because voluntary after-tax contributions are not a percentage of pay.

“And so the voluntary after tax contribution is not a percentage of your self-employment compensation. So unlike the employer contribution, you can contribute a 100% dollar for dollar up to the overall limit as a voluntary after tax contribution.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial
(20:22 in the webinar)

The Mega Backdoor Roth is a two-step process. First, the partner makes a voluntary after-tax contribution. Second, the partner converts it to Roth, either in the plan to the Roth Solo 401(k) or out of the plan to a Roth IRA.

The partner still subtracts one-half of self-employment tax first, so the K-1 figure exceeds the compensation figure.

“So, if you’re under age 50, you want to make a $72,000 voluntary after tax contribution. You would need to have at least $77,473.32 reported on box 14 code A of the K-1 that you received from the partnership …”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial
(20:58 in the webinar)

What K-1 income does each age band need?

  • Under age 50: $77,473.32 supports a $72,000 voluntary after-tax contribution.
  • Age 50 to 59 or 64 and older: $86,081.46 supports $80,000, which adds the $8,000 catch-up.
  • Age 60 to 63: $89,578.52 supports $83,250, which adds the $11,250 super catch-up.

How is a Solo 401(k) for partnerships set up with multiple partners?

Solo 401(k) for partnerships uses a single plan sponsored by the partnership, with a separate account for each partner and each fund type.

The partnership can sponsor the plan when it has no non-owner, non-spouse employees. Each partner must also report their own earned self-employment income in Box 14 of Schedule K-1. \

Each partner chooses their own contribution types and amounts, subject to the limits and deadlines. One partner may maximize Roth while another maximizes pre-tax. Two partners who each want pre-tax, Roth, and after-tax money need six accounts in total. \

How do you make Mega Backdoor Roth and catch-up contributions in practice?

Solo 401(k) for partnerships handles Mega Backdoor Roth and catch-up contributions through at least two accounts at the participant’s bank or brokerage, such as Fidelity or Schwab.

“I’m interested in doing the Mega Backdoor Roth and catch-up. How do I exactly do this logistically if I have the self-employment income?”

— Question from webinar attendee Lisa, read aloud by George Blower, Retirement Accounts Attorney, My Solo 401k Financial
(25:48 in the webinar)

“Now, it’s noteworthy that the catch-up and the super catch-up contributions are not made as voluntary after tax contributions. … So you can make an $8,000 direct Roth catch-up contribution and then another $72,000 voluntary after tax contribution that’s then converted to the Roth.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial
(21:55 in the webinar)

A Roth account receives the catch-up contribution. A separate after-tax account receives the voluntary after-tax contribution. The participant then moves the after-tax money to the Roth Solo 401(k) or to a Roth IRA, including one the participant already owns.

Can Roth Solo 401(k) money move out to a Roth IRA?

Roth Solo 401(k) money generally needs a triggering event, typically age 59½, before it can move out of the plan. Voluntary after-tax contributions are an exception. Anyone can transfer them to a Roth IRA when the plan allows it.

Info: Most participants move after-tax dollars to Roth immediately. Gains earned while invested in the after-tax account are taxable when transferred to Roth, according to the webinar.

This article is based on the November 4, 2026 live webinar hosted by My Solo 401k Financial. 

Next step: Open a Solo 401(k) built for partnerships.

My Solo 401k Financial prepares plan documents to establish a Solo 401(k) within the same business day. Open a Solo 401(k) account with My Solo 401k Financial.

Educational purposes only: This content is provided for educational purposes only. It is not tax, legal, or investment advice, and it is not a solicitation. Consult a tax attorney and a financial professional before making an investment decision.


Self-Directed Solo 401k: No Minimum Contribution, $50,000 Loans, $1,500 Credit, Mega Backdoor Roth

Self-Directed Solo 401k

By Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial · Published

Direct answer: A Self-Directed Solo 401k is a 401(k) plan for business owners with no eligible non-owner W-2 employees. The owner serves as trustee and chooses where the plan’s funds are held. The plan has its own EIN. For 2026, total contributions are capped at $72,000, plus catch-up contributions for owners age 50 or older.

Key Takeaways

  • The 2026 Self-Directed Solo 401k overall contribution limit is $72,000, with an $8,000 catch-up at age 50+ or an $11,250 super catch-up at ages 60–63.
  • The 2026 employee deferral limit is $24,500, and it is aggregated with any day-job 401(k) deferrals.
  • Employer profit-sharing and voluntary after-tax contributions are not aggregated with a day-job 401(k).
  • An S corporation owner paying $72,000 in W-2 wages can contribute the full $72,000 as voluntary after-tax contributions for the Mega Backdoor Roth.
  • Under SECURE 2.0, S corporation and C corporation owners whose prior-year Social Security wages exceed $150,000 must make 2026 catch-ups as Roth.
  • A Self-Directed Solo 401k is a separate retirement trust that needs its own EIN, used for brokerage accounts and Form 1099-R reporting.
  • Form 5500-EZ is required once total plan assets exceed $250,000, and a final return is required whenever the plan closes.

Status: As of , the Self-Directed Solo 401k limits in this article are the enacted 2026 figures. The SECURE 2.0 mandatory Roth catch-up rule is effective for tax year 2026.

Video: the live webinar on how a Self-Directed Solo 401k works, hosted by My Solo 401k Financial.

How does a self-directed Solo 401k work?

A Self-Directed Solo 401k works like any other 401(k), except it covers only the business owner and a working spouse. The self-employed business sponsors the plan. The owner acts as trustee, picks the financial institution that holds the funds, and selects the investments.

The plan document controls which features are available. A plan drafted for maximum flexibility can allow the Mega Backdoor Roth, participant loans, and employee and employer Roth contributions. It can also allow alternative investments such as real estate, precious metals, crypto, tax liens, and private equity.

All 401(k) rules still apply. Personal and business funds cannot be commingled with plan funds. The prohibited transaction rules in IRC 4975 govern every investment.

Who qualifies for a Self-Directed Solo 401k?

A Self-Directed Solo 401k requires self-employment income and no non-owner W-2 employees working 1,000 or more hours a year. A spouse working in the business can participate in the same plan.

The long-term part-time employee rule

The SECURE Act created the long-term part-time employee rule with a three-year period. SECURE 2.0 shortened it to two years. A non-owner W-2 employee working 500–999 hours for two consecutive years ends Solo 401k eligibility.

Controlled group and affiliated service group rules

Owning another business with W-2 employees can disqualify an owner from a Solo 401k, even for a separate owner-only business. The controlled group rules apply 50% and 80% ownership tests. The affiliated service group rules can also apply.

How much self-employment activity is enough?

Self-Directed Solo 401k eligibility turns on performing material services, not on a minimum number of hours or a minimum income. IRS Publication 560 does not set an hour or dollar threshold [VERIFY: transcript says “publication number five”; Publication 560 covers self-employed retirement plans]. Day trading on your own account is typically not earned income from self-employment.

“So whether you’re doing a few hours a year or ten hours a year, that doesn’t matter. What matters is that you were actually doing the work.”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial (46:41 in the webinar)

The webinar gave a two-part rule of thumb. First, actually do the work. Second, report the self-employment activity on the applicable tax return.

What are the 2026 Self-Directed Solo 401k contribution limits?

The 2026 Self-Directed Solo 401k overall limit is $72,000 across all contribution types. Catch-up contributions sit on top of that limit. The age 50+ catch-up is $8,000, up from $7,500 in 2025. Owners ages 60 through 63 can instead make an $11,250 super catch-up, but not both.

“So for 2026 … the overall contribution limit is $72,000 to a Solo 401(k), then you’ve got the $8,000 catch-up for those who are age 50 or older.”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial (2:40 in the webinar)
2026 Self-Directed Solo 401k contribution types compared
Contribution type 2026 limit Aggregated with a day-job 401(k)? Catch-up allowed?
Employee deferral (pre-tax or Roth) $24,500 Yes Yes: $8,000 at 50+, or $11,250 at ages 60–63
Employer profit sharing (pre-tax or Roth) 25% of W-2 wages for an S corporation, within $72,000 No No
Voluntary after-tax (Mega Backdoor Roth) Dollar for dollar of earned income, within $72,000 No No
All types combined $72,000 Employee portion only Catch-up is added on top

Table summary: In 2026, employee deferrals cap at $24,500 and are shared with a day-job 401(k), while all Self-Directed Solo 401k contribution types together cap at $72,000 plus catch-up.

Attendee question: the AI-generated contribution math

“AI tells me I can contribute up to $30,500 of my wages if I’m 50 or older and add an additional 25% employer contribution totaling $38,125. However, it also says the annual contribution limit is $76,500. How do I contribute the additional funds?”

— Webinar attendee, answered by Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial (2:10 in the webinar)

The webinar’s advice was to treat AI as a resource, not the source. The $30,500 figure reflects 2025 employee numbers. For 2026, the employee deferral is $24,500 plus an $8,000 catch-up, or $32,500. Additional room comes from employer profit-sharing or voluntary after-tax contributions, up to the $72,000 overall limit plus catch-up.

How are Self-Directed Solo 401k contributions calculated by entity type?

Self-Directed Solo 401k contributions must be supported by earned income from self-employment. Interest and capital gains do not count. The entity type determines which tax figure drives the calculation.

Earned income figure used for Self-Directed Solo 401k contributions, by business entity type
Entity type Earned income figure Mandatory Roth catch-up can apply?
Sole proprietorship or single-member LLC Schedule C, line 31 No
S corporation or LLC taxed as an S corporation W-2 Box 1 gross wages Yes
C corporation W-2 wages Yes
LLC taxed as a partnership Schedule K-1 self-employment income No

Table summary: Sole proprietors use Schedule C line 31, corporations use W-2 wages, and partnerships use K-1 self-employment income; only W-2 owners face the mandatory Roth catch-up.

The SECURE 2.0 mandatory Roth catch-up

Starting in tax year 2026, SECURE 2.0 requires some catch-ups to be made as Roth. The rule applies when prior-year Social Security wages on the W-2 exceed $150,000. Only S corporation and C corporation owners are affected, because only they receive W-2 wages from the business.

Day-job 401(k) plus a Self-Directed Solo 401k

Owners who also participate in an employer’s 401(k) share one employee deferral limit across both plans. Employer profit-sharing and voluntary after-tax contributions are not shared. A moonlighting owner can often skip Solo 401k employee deferrals and use the other two sources.

How does the Mega Backdoor Roth work in a Self-Directed Solo 401k?

A Self-Directed Solo 401k that allows voluntary after-tax contributions supports the Mega Backdoor Roth Solo 401k strategy. After-tax dollars are converted to the Roth Solo 401k or a Roth IRA. My Solo 401k Financial has offered the strategy since 2013.

“So as long as you pay yourself at least $72,000 of W-2 wages, for tax year 2026, you can contribute that entire $72,000 to the voluntary after tax Solo 401(k) and then turn around and convert it…”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial (33:15 in the webinar)

Example: An S corporation owner pays herself $72,000 in W-2 wages for 2026. Voluntary after-tax contributions are dollar for dollar, so she can contribute the full $72,000 after-tax. She then converts it to Roth. No further contributions fit, because the overall limit is used up.

If she pays herself $80,000 instead, the after-tax maximum is still $72,000. Catch-up contributions can never go into the voluntary after-tax account.

Attendee question: is there a waiting period before converting?

“Once I’ve made after tax contributions to my 401(k) after tax account, do I need to wait a day to convert to a Roth IRA?”

— Webinar attendee, answered by Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial (37:20 in the webinar)

The regulations impose no waiting period. Funds may need to clear the bank or brokerage account first for logistical reasons. Every conversion requires Form 1099-R reporting, even though it is non-taxable.

How the pro rata rule is satisfied

The Self-Directed Solo 401k Mega Backdoor Roth avoids IRA-style pro rata aggregation through a separate holding account titled for voluntary after-tax funds. Convert everything in that account at the time of conversion. Interest that trickles in afterward can be converted with the next conversion.

Why does a Self-Directed Solo 401k need its own EIN?

A Self-Directed Solo 401k is a retirement trust and a separate legal entity, so it needs its own employer identification number. The business EIN and the owner’s Social Security number cannot be used. The plan EIN goes on the plan’s bank and brokerage accounts. It is also used for Form 1099-R reporting of RMDs, in-plan conversions, and Mega Backdoor Roth conversions.

What does checkbook control mean for a Self-Directed Solo 401k?

Checkbook control and Self-Directed Solo 401k are interchangeable industry terms. The owner chooses where the plan’s funds are held, and only the owner can access them.

“Checkbook control is an industry wide terminology to refer to a self directed Solo 401(k). With the self-directed Solo 401(k), checkbook control means that you get to choose where to hold the funds at for that Solo 401(k).”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial (48:13 in the webinar)

Most alternative investments are now funded by wire, not paper check. Funds move from the plan’s brokerage or bank account to the title company or private fund. Equities remain fully available, and many clients invest only in equities.

Where the funds are held

Fidelity and Schwab offer their own basic Solo 401k plans. Both also open brokerage accounts for an outside provider’s plan. Fidelity calls these non-prototype, investment-only accounts. Schwab calls them company retirement brokerage accounts.

How do you open and fund a Self-Directed Solo 401k?

A Self-Directed Solo 401k is opened in a defined sequence, as described in the webinar.

  1. Confirm eligibility: self-employment income and no eligible non-owner W-2 employees.
  2. Identify the sponsoring business: your own name for a sole proprietorship, or the LLC or corporation otherwise.
  3. Complete the online questionnaire. Plan documents are delivered the same day by download link.
  4. Sign and upload the documents, then choose the financial institution to hold the funds.
  5. Obtain the plan’s own EIN.
  6. Open the plan’s brokerage or bank accounts.
  7. Make contributions, or transfer IRAs and former employer plans.
  8. Invest in equities, alternative investments, or both.

Transfers and rollovers into the plan

“It’s worth noting that the transfer of IRAs and former employer plans to the Solo 401(k) do not count towards your annual contribution limit. For example, you might transfer a $500,000 IRA to the Solo 401(k).”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial (23:13 in the webinar)

A Self-Directed Solo 401k can accept 403(b) plans, Thrift Savings Plans, 457(b) plans, 401(k) plans, and defined benefit plans. It can also accept profit-sharing plans, pension plans, and traditional, SIMPLE, and SEP IRAs. Roth IRAs and non-deductible IRA basis can never be transferred in. Non-deductible IRA gains can be.

Moving an existing plan

A Solo 401k at Fidelity, Schwab, or E*TRADE can be moved to another provider through a restatement. A restatement is neither taxable nor reportable. No Form 1099-R or final Form 5500-EZ is issued, because the plan is not closing.

What other features does a Self-Directed Solo 401k include?

Participant loans

Self-Directed Solo 401k participant loans can reach 50% of the balance, up to $50,000. The plan’s minimum is $1,000. Repayments come from personal funds, with interest typically set at prime plus one point. Terms run five years, or 15 to 30 years when used toward a primary residence.

The $1,500 auto contribution credit

The webinar described a $1,500 auto contribution credit, claimed at $500 a year for three years on Form 8881. The credit reduces business taxes dollar for dollar. Per the webinar, it does not require making plan contributions, only eligibility, earned income, and a plan that includes the feature [VERIFY: confirm IRC 45T credit eligibility for owner-only plans]. The credit originates in the SECURE Act and is distinct from the startup-cost tax credit.

Form 5500-EZ reporting

Self-Directed Solo 401k assets above $250,000 at plan year-end trigger Form 5500-EZ, typically due in July. All holding accounts and both spouses’ balances are added together. A final Form 5500-EZ is required whenever the plan closes, regardless of value.

Self-Directed Solo 401k vs. Self-Directed IRA

A Self-Directed Solo 401k is usually preferred over a Self-Directed IRA by owners who qualify, according to the webinar. The trade-off is eligibility: only owner-only businesses qualify.

Self-Directed Solo 401k compared with a Self-Directed IRA
Account Who qualifies Participant loans Contribution capacity $1,500 auto contribution credit Annual cost
Self-Directed Solo 401k Self-employed, owner-only business Yes, up to $50,000 $72,000 in 2026, plus catch-up Yes Typically lower
Self-Directed IRA Anyone with an IRA No IRA limits only No Typically higher

Table summary: A Self-Directed Solo 401k offers loans, higher contributions, and the auto contribution credit at lower cost, but only owner-only businesses qualify.

Learn more about the full self-directed Solo 401k plan and its features.

Frequently Asked Questions

What is the Solo 401k contribution limit for 2026?

The 2026 Self-Directed Solo 401k overall limit is $72,000 across employee, employer, and voluntary after-tax contributions. The employee deferral portion is capped at $24,500. Owners age 50 or older can add an $8,000 catch-up. Owners ages 60 through 63 can instead add an $11,250 super catch-up.

Does my Solo 401k need its own EIN?

Yes. A Self-Directed Solo 401k is a separate retirement trust, so it needs its own employer identification number. Your business EIN and Social Security number cannot be used. The plan EIN is used to open the plan’s brokerage accounts and for Form 1099-R reporting of conversions and distributions.

Do I have to wait before converting after-tax Solo 401k contributions to Roth?

No. The regulations require no waiting period between a voluntary after-tax contribution and its Mega Backdoor Roth conversion. Your bank or brokerage may need the deposit to clear first. Convert the full balance of the after-tax account each time. Each conversion is reported on Form 1099-R.

How much self-employment activity do I need for a Solo 401k?

No minimum hours or income are set. A Self-Directed Solo 401k requires that you perform material services for the business, even part time, and report the activity on your tax return. A few hours a year can qualify if you actually do the work. Day trading your own account typically does not.

Is there a minimum annual contribution for a Solo 401k?

No. A Self-Directed Solo 401k is a defined contribution plan, not a defined benefit plan, so contributions are optional each year. You can contribute any amount up to the limit, or nothing. You cannot contribute in a year without earned income from self-employment.

Do I have to make contributions to get the $1,500 auto contribution credit?

According to the webinar, no. The $1,500 auto contribution credit is claimed at $500 a year for three years on Form 8881. Per the webinar, you must qualify for a Solo 401k, have self-employment earned income, and use a plan that includes the feature. Contribution amounts do not affect it.

Can I roll my 403(b) or old 401k into a Solo 401k?

Yes. A Self-Directed Solo 401k can accept 403(b), 457(b), TSP, 401(k), pension, and profit-sharing plans. It can also accept traditional, SIMPLE, and SEP IRAs. Transfers do not count toward the annual limit. Roth IRAs and non-deductible IRA basis cannot be transferred in.

What happens to my Solo 401k if my self-employment ends?

When self-employment permanently stops, regulators expect the Self-Directed Solo 401k to be closed. The funds are typically transferred to an IRA or to a new employer’s plan. Closing the plan requires a final Form 5500-EZ regardless of balance.

Glossary

Self-Directed Solo 401k
A 401(k) for owner-only businesses where the owner is trustee, chooses where funds are held, and may invest in alternative assets.
Checkbook control
The owner-trustee’s ability to choose the plan’s financial institution and move plan funds directly into investments.
Voluntary after-tax contribution
A non-deductible Solo 401k contribution, held in a separate account and typically converted to Roth.
Mega Backdoor Roth
Converting voluntary after-tax Solo 401k funds to the Roth Solo 401k or a Roth IRA.
Restatement
Replacing an existing plan’s documents with a new provider’s documents, without closing the plan.
Controlled group
Businesses treated as one employer under 50% and 80% common-ownership tests for retirement plan eligibility.

This article is based on the [VERIFY: webinar date] live webinar hosted by My Solo 401k Financial. Analysis by Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial.

Ready to take checkbook control of your retirement savings?

Open a Self-Directed Solo 401k with the Mega Backdoor Roth, participant loans, and your choice of where to hold the funds.

Open a Solo 401k account

Educational purposes only: This article is for general educational purposes. It is not tax, legal, or investment advice. Consult a qualified professional about your situation.

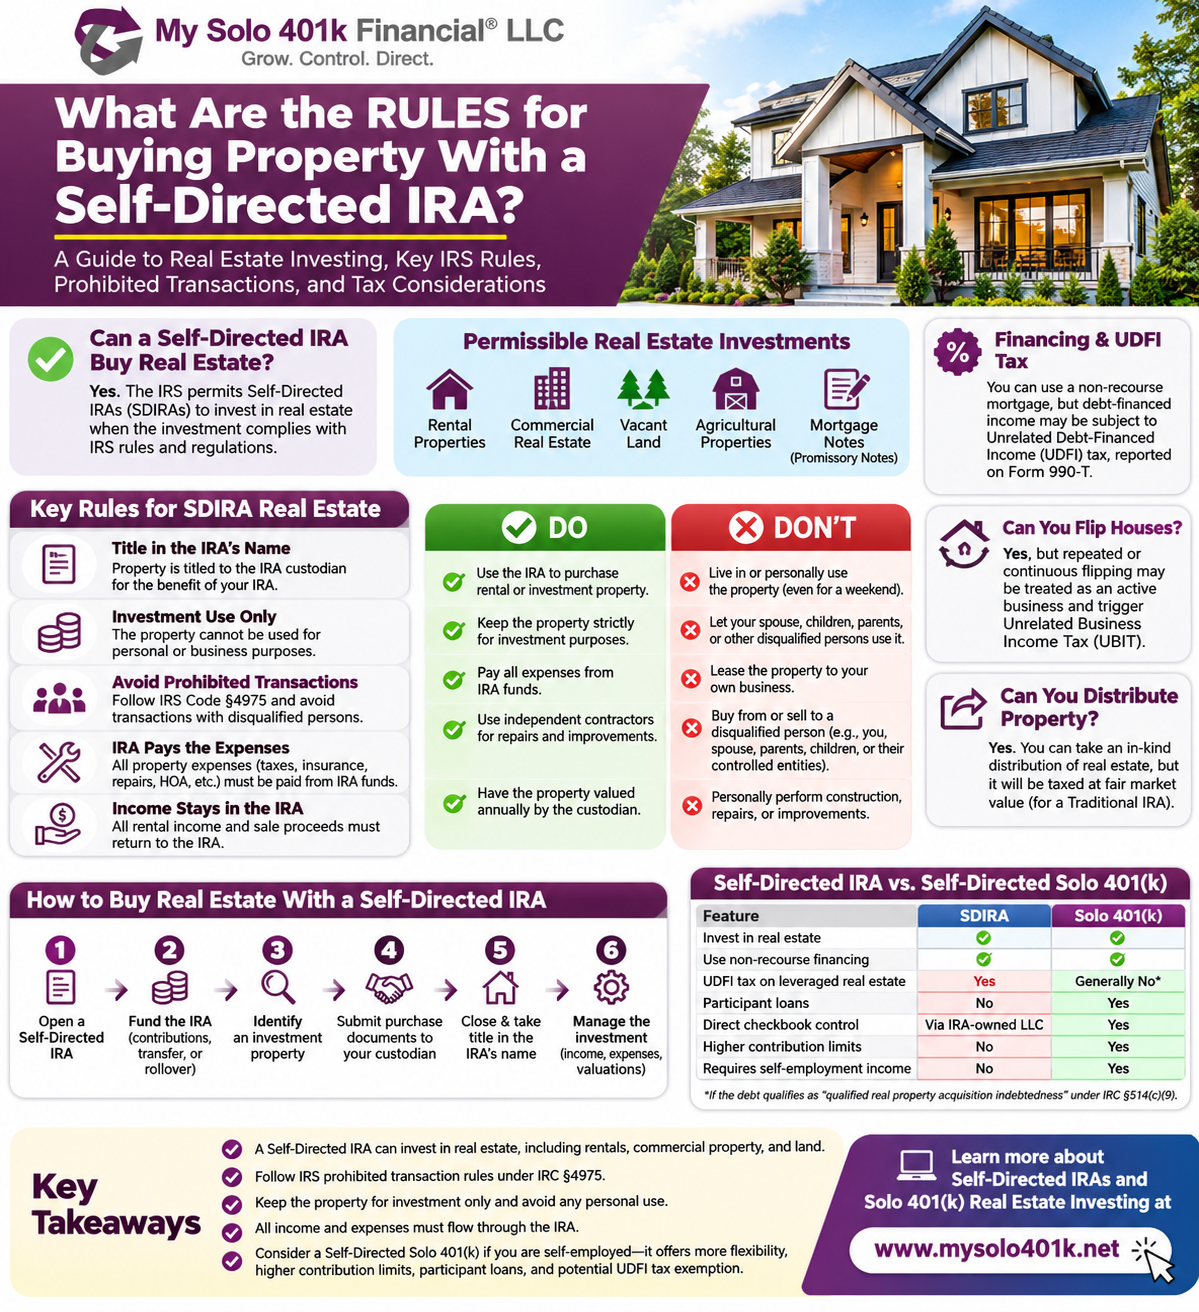
Self-Directed IRA Real Estate Rules: Not One Day of Personal Use (IRC 4975)

Self-Directed IRA Real Estate Rules: Not One Day of Personal Use (IRC 4975)

By Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial · Published

Direct answer: Self-Directed IRA real estate is legal, but the property must be held purely as an investment. Title goes in the custodian’s name for the benefit of the IRA. The IRA pays every expense and receives every dollar of income. Neither the owner nor any disqualified person may use, repair, buy, sell, or lease the property, even at fair market rent.

Key Takeaways

  • Title to Self-Directed IRA real estate is held in the IRA custodian’s name for the benefit of the IRA, never in the owner’s personal name.
  • IRC 4975 prohibited-transaction rules bar personal use of IRA-owned property, even for one day a year and even at fair market rent.
  • The IRA owner, spouse, lineal ancestors, lineal descendants, and IRA service providers are disqualified persons; siblings, aunts, and uncles generally are not.
  • A Self-Directed IRA can borrow only through a non-recourse loan, and debt-financed income above a $1,000 specific deduction is taxed as UDFI on Form 990-T.
  • In the webinar’s example, $30,000 of annual rent minus $12,000 of taxes, insurance, and maintenance leaves $18,000 growing inside the IRA.
  • The webinar’s rule of thumb is no more than one or two house flips per year in a Self-Directed IRA, alongside other passive investments.
  • A self-directed Solo 401(k) can use a non-recourse loan without UDFI under IRC 514(c)(9), but only self-employed owners without eligible employees qualify.

Status: As of , the Self-Directed IRA real estate rules in this article reflect current federal law under IRC 408, IRC 4975, and IRC 511–514. None of them is a pending proposal.

Video: the live webinar on Self-Directed IRA Real Estate rules, hosted by My Solo 401k Financial.

What are the rules for buying property with a self-directed IRA?

Self-Directed IRA real estate purchases follow six core rules from the webinar. The custodian holds title for the IRA. The property is for investment only. No transaction may involve a disqualified person. The IRA pays all expenses. All income returns to the IRA. Any loan must be non-recourse.

A Self-Directed IRA is an IRA whose custodian permits alternative assets such as real estate. Conventional brokerage and bank IRAs usually do not allow those assets.

What types of real estate can a Self-Directed IRA hold?

Self-Directed IRA real estate can include residential rentals, commercial buildings, vacant land, and agricultural property. A Self-Directed IRA can also hold promissory notes secured by real estate. The IRS permits these holdings as long as they comply with the IRA rules and the prohibited-transaction rules.

How is title held on Self-Directed IRA real estate?

Self-Directed IRA real estate is titled in the name of the IRA custodian or trust company for the benefit of the owner’s IRA. The owner is not personally investing. The IRA is the buyer, so the deed never carries the owner’s personal name.

Can you personally use Self-Directed IRA real estate?

Self-Directed IRA real estate cannot be used personally by the owner or any disqualified person. The ban has no minimum-use exception. Paying fair market rent does not cure it.

“So again, you cannot use that property for personal use, even if you use it one day out of the year, or even if you pay fair market rate, that’s not allowed.”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial (3:11 in the webinar)

Important: The webinar listed these as prohibited uses of IRA-owned property:

  • Living in a house the IRA owns.
  • Spending a weekend at an IRA-owned vacation rental.
  • Letting your children or parents stay in an IRA-owned property.
  • Leasing IRA-owned commercial space to your own business.

Who is a disqualified person for Self-Directed IRA real estate?

Self-Directed IRA real estate cannot be bought from, sold to, leased to, or lent to a disqualified person. IRC 4975 defines that group. Any such dealing is a prohibited transaction.

“So specifically the IRS code section that applies to IRAs is IRC code 4975. And a self-directed IRA cannot engage in prohibited transactions with individuals or entities.”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial (5:18 in the webinar)
Disqualified-person status for Self-Directed IRA real estate transactions, as described in the webinar
Person or entity Disqualified? Note
IRA owner Yes Cannot use, repair, buy from, or sell to the IRA.
Spouse Yes Treated the same as the owner.
Parents and other lineal ancestors Yes Cannot stay in or rent IRA property.
Children and other lineal descendants Yes Cannot stay in or rent IRA property.
Owner’s business Yes Cannot lease IRA-owned commercial space.
IRA custodian and service providers Yes Cannot use the property personally.
Siblings, aunts, uncles Generally no A sale meant to route the property back to you is still prohibited.

Table summary: The owner, spouse, ancestors, descendants, the owner’s business, and IRA service providers are disqualified persons; siblings, aunts, and uncles generally are not.

Straw-man and roundabout transactions

Self-Directed IRA real estate cannot be passed through a non-disqualified party to reach you. The webinar gave two examples. Selling the property to your brother so you can buy it back is prohibited. So is selling your home to a neighbor so your IRA can buy it from the neighbor.

Can you repair or renovate Self-Directed IRA real estate yourself?

Self-Directed IRA real estate must be repaired by an unrelated third-party contractor, not by the owner. Sweat equity from you, your spouse, your parents, or your children raises prohibited-transaction concerns. The concern is greatest when the work raises the account’s value.

“Yes, you might be handy, but unfortunately, you can’t show off your skills on your property owned by your self-directed IRA. You’re gonna have to save those skills for property you own personally.”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial (18:07 in the webinar)

Prohibited hands-on work

The webinar listed fixing a toilet, painting, replacing flooring or a roof, and installing cabinets as prohibited hands-on work. Electrical or plumbing repairs are also prohibited. Personally supplying construction materials is too, because materials are an IRA expense.

Permitted management tasks

The owner may still manage Self-Directed IRA real estate without compensation. Finding tenants and hiring contractors are managerial functions, not sweat equity.

How do expenses and rental income flow in Self-Directed IRA real estate?

Self-Directed IRA real estate expenses must be paid from IRA funds. Those expenses include property taxes, insurance, HOA fees, repairs, maintenance, and renovations. All income must flow directly back to the IRA, including rent, security deposits, and sale proceeds.

Rent cannot pass through your personal bank account, even if you later deposit it into the IRA. Plan ahead so the IRA does not run short of cash. If it does, you can make an annual IRA contribution within the limits. You can also transfer other IRAs or former employer plans into it.

“So as this slide here illustrates, let’s say the annual rent is $30,000, taxes, insurance and maintenance is $12,000. The IRA has $18,000 remaining from that investment.”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial (9:47 in the webinar)

Example: A Self-Directed IRA rental collects $30,000 in annual rent. The IRA pays $12,000 for taxes, insurance, and maintenance. The remaining $18,000 stays in the IRA, tax-deferred, and can be reinvested. In a Self-Directed Roth IRA, the same growth would be tax-free if distributions are qualified.

Can a Self-Directed IRA get a mortgage to buy real estate?

Self-Directed IRA real estate can be financed, but only with a non-recourse loan. The loan is made to the IRA, and the IRA makes every payment. The owner cannot personally guarantee it. A recourse loan is never allowed for an IRA.

If the IRA defaults, the lender’s only remedy is the financed property. The lender cannot reach your personal assets or other assets in the IRA. It also cannot reach your other IRAs or your Solo 401(k).

UDFI: the tax on debt-financed income

Self-Directed IRA real estate bought with borrowed money produces unrelated debt-financed income (UDFI) on the debt-financed share. The IRA pays the tax, not the owner. The IRA reports it on Form 990-T.

“So the first $1,000 is exempt from that unrelated debt finance income tax, but any amount after that is subject to that unrelated debt finance income tax.”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial (26:12 in the webinar)

Important: The webinar noted the UDFI tax rate “can be pretty high,” citing rates as high as 38% [VERIFY: compressed trust tax brackets top out at 37% under current law]. Keep enough cash in the IRA to pay the tax.

Can you flip houses with Self-Directed IRA real estate?

Self-Directed IRA real estate flipping is allowed, but frequent flipping can trigger unrelated business income tax (UBIT). Congress designed IRAs for passive, buy-and-hold investing. The IRS distinguishes passive investment from a regularly conducted business.

The webinar’s guidance is to hold a property for a year or longer so it is more likely to be treated as passive. A large number of short-term flips generally triggers UBIT. Like UDFI, UBIT is paid by the IRA and reported on Form 990-T.

“The rule of thumb I see in the industry is to perform no more than one or two flips a year inside that self-directed IRA. And that’s not the sole activity being done through that IRA.”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial (33:29 in the webinar)

How do valuations, RMDs, and in-kind distributions work for Self-Directed IRA real estate?

Self-Directed IRA real estate needs a fair market valuation each year. The custodian reports the IRA’s value, including the property, to the IRS on Form 5498. Every purchase and sale should also happen at fair market value.

An in-kind distribution moves the property, or part of it, out of the IRA into your name. You pay tax on its appraised value. Required minimum distributions (RMDs) can be satisfied this way.

Partial distribution does not unlock personal use. You may use the property only after it is fully distributed out of the IRA.

What happens if Self-Directed IRA real estate triggers a prohibited transaction?

A prohibited transaction involving Self-Directed IRA real estate typically makes the entire IRA taxable. The deemed distribution is dated to the year the transaction occurred, not the year the IRS finds it. If discovery comes two or three years later, penalties and interest compound on the back taxes.

How do you buy property with a Self-Directed IRA, step by step?

A Self-Directed IRA real estate purchase follows the sequence below, as presented in the webinar.

  1. Open a Self-Directed IRA with a custodian that holds real estate. The webinar named Forge Trust as one example among many.
  2. Transfer existing IRAs or former employer plans into the Self-Directed IRA.
  3. Identify the property.
  4. Prepare the purchase contract. The custodian signs the required IRA investment documents.
  5. Pay the escrow deposit from the Self-Directed IRA.
  6. Wire the purchase funds from the Self-Directed IRA directly to the title company.
  7. Take title in the name of the Self-Directed IRA.
  8. Route all future expenses, rent, and sale proceeds through the Self-Directed IRA.

Self-Directed IRA vs. self-directed Solo 401(k) for real estate

Self-Directed IRA real estate investors who are self-employed may do better with a self-directed Solo 401(k), according to the webinar. The main advantage is debt financing. A non-recourse loan inside a Solo 401(k) does not trigger UDFI, under the qualified-plan exception in IRC 514(c)(9).

Eligibility is the limit. A self-directed Solo 401(k) plan requires self-employment and no non-owner W-2 employees working 1,000 or more hours a year. The long-term part-time rule also applies to employees working 500–999 hours for two consecutive years.

Self-Directed IRA compared with a self-directed Solo 401(k) for real estate investing
Account Who qualifies Non-recourse loan tax Participant loans Checkbook control Annual reporting
Self-Directed IRA Anyone with an IRA UDFI above $1,000; Form 990-T Not available Requires an IRA LLC (checkbook IRA) Form 5498, filed by the custodian
Self-directed Solo 401(k) Self-employed, no eligible non-owner employees No UDFI (IRC 514(c)(9)) 50% of balance, up to $50,000 Built in Form 5500-EZ once assets exceed $250,000

Table summary: A self-directed Solo 401(k) avoids UDFI on non-recourse loans, allows participant loans, and includes checkbook control, but only self-employed owners qualify.

2026 Sole Proprietor Solo 401k: Exact Income Needed to Max Out Contributions

2026 Solo 401(k) Income Thresholds: $252,317.72 for the $72,000 Max

Direct Answer:

The 2026 Solo 401(k) income thresholds for sole proprietors depend on the contribution type. A sole proprietor with no day-job plan needs $252,317.72 of Schedule C line 31 net income for the $72,000 pre-tax maximum. A $72,000 Mega Backdoor Roth contribution requires $77,473.32 for those under age 50. A sole proprietor who already maxed a day-job 401(k) needs $376,480.35 for a $72,000 employer contribution.

Key takeaways on the 2026 Solo 401(k) income thresholds

  • The 2026 overall Solo 401(k) limit is $72,000 for all contribution types, rising to $80,000 with an $8,000 catch-up and $83,250 with an $11,250 super catch-up.
  • The 2026 employee deferral limit is $24,500, and a sole proprietor’s employer contribution is capped at 20% of self-employment compensation.
  • A sole proprietor needs $252,317.72 of Schedule C line 31 net income to make $72,000 in pre-tax contributions: $24,500 as employee and $47,500 as employer.
  • A sole proprietor who made the $24,500 employee deferral to a day-job 401(k) needs $376,480.35 of line 31 net income for a $72,000 employer contribution.
  • A sole proprietor under age 50 needs $77,473.32 of line 31 net income for a $72,000 Mega Backdoor Roth contribution, and $89,578.52 at ages 60 to 63 for $83,250.
  • Day-job 403(b) contributions count toward the $72,000 overall limit alongside Solo 401(k) contributions, but day-job 401(k) employee deferrals do not reduce the Solo 401(k) employer or after-tax limits.
  • Establishing the Solo 401(k) by December 31, 2026 preserves 2026 contributions until the 2026 business tax return deadline, including any timely filed extension.

Video: 2026 Solo 401(k) income thresholds for sole proprietors, from the My Solo 401k Financial live webinar.

How much Schedule C income do I need to max out a Solo 401(k) in 2026?

The 2026 Solo 401(k) income thresholds are measured on Schedule C line 31, the net income line for a sole proprietorship. A sole proprietor subtracts one half of the self-employment tax from line 31 to reach self-employment compensation. Solo 401(k) limits apply to that compensation figure.

An LLC taxed as a sole proprietorship follows the same rule as an unincorporated sole proprietor or 1099 independent contractor.

2026 Solo 401(k) income thresholds: Schedule C line 31 income needed, by scenario and age
Scenario Age at end of 2026 Total contribution justified Line 31 income needed
Pre-tax maximum, no other plan contributions Under 50 $72,000 ($24,500 employee + $47,500 employer) $252,317.72
Pre-tax maximum, no other plan contributions 50 to 59, or 64 and older $80,000 $252,317.72
Pre-tax maximum, no other plan contributions 60 to 63 $83,250 $252,317.72
Employer-only pre-tax, $24,500 employee deferral made to a day-job 401(k) Not stated by age $72,000 employer contribution $376,480.35
Mega backdoor Roth, no other plan contributions Under 50 $72,000 $77,473.32
Mega backdoor Roth, no other plan contributions 50 to 59, or 64 and older $80,000 ($72,000 after tax + $8,000 Roth catch-up) $86,081.46
Mega backdoor Roth, no other plan contributions 60 to 63 $83,250 ($72,000 after tax + $11,250 Roth super catch-up) $89,578.52


Important: The Mega Backdoor Roth rows assume no other contributions to the Solo 401(k) and no 403(b) contributions in 2026. Each row also assumes the sole proprietor has the self-employment income shown.

What are the 2026 Solo 401(k) contribution limits?

The 2026 Solo 401(k) contribution limits consist of one overall cap and several sublimits. A Solo 401(k) plan carries the highest limits of any defined contribution plan available to self-employed individuals, because separate contribution buckets can each be filled.

“So, your overall contribution limit for all types of contributions being made to the Solo 401(k) is the lesser of your self-employment compensation up to $72,000.”

— George Blower, Retirement Accounts Attorney
(10:50 in the webinar)

Overall limit and catch-up contributions

The 2026 Solo 401(k) overall limit is the lesser of self-employment compensation or $72,000. Participants age 50 to 59, or 64 and older, at the end of 2026 may add an $8,000 catch-up contribution, for a total of $80,000. Participants age 60 to 63 may add an $11,250 super catch-up contribution, for a total of $83,250.

Employee, employer, and after-tax buckets

The 2026 Solo 401(k) employee deferral limit is $24,500. A sole proprietor’s employer contribution is limited to 20% of self-employment compensation. A voluntary after tax contribution can equal 100% of self-employment compensation, up to the overall limit.

What counts as self-employment income for Solo 401(k) contributions?

Solo 401(k) contributions are limited by self-employment income, because contributions cannot exceed what the business owner earns. A sole proprietor measures that income as Schedule C line 31 less one half of the self-employment tax. My Solo 401k Financial offers a calculator on its website for that pre-calculation.

What counts

Net income from an unincorporated business, a 1099 independent contractor business, or an LLC taxed as a sole proprietorship counts as Solo 401(k) self-employment income.

What does not count

  • W-2 wages from a day job do not justify Solo 401(k) contributions.
  • Gross business revenue does not count, because expenses and one half of the self-employment tax are subtracted first.
  • Investment income, such as Schedule E income, does not count. Schedule C income is self-employment income.

Important: A person with a high-paying W-2 job can still have a Solo 401(k) if no employees work for any business owned by that person or a spouse. Contribution capacity then depends on the side business income, not the W-2 wages.

What income maximizes pre-tax Solo 401(k) contributions in 2026?

The pre-tax 2026 Solo 401(k) income threshold is $252,317.72 of Schedule C line 31 net income for a sole proprietor with no day job. That income supports $72,000 in pre-tax contributions: the $24,500 employee deferral plus a 20% employer contribution of $47,500.

“If you have at least $252,317.72 of line 31 Schedule C income … you could contribute $24,500 as a pre-tax employee contribution because that’s going to be a 100% of your self-employment compensation up to $24,500 plus 20% of your self-employment income.”

— George Blower, Retirement Accounts Attorney
(15:53 in the webinar)

Example: A sole proprietor under age 50 reports $252,317.72 on line 31. After one half of the self-employment tax, self-employment compensation is $237,500. The $24,500 employee deferral plus a 20% employer contribution of $47,500 totals $72,000 pre-tax.

Pre-tax thresholds at age 50 and older

The same $252,317.72 line 31 income supports $80,000 in pre-tax contributions at ages 50 to 59 or 64 and older. The same income supports $83,250 at ages 60 to 63. Catch-up and super catch-up contributions go into the same pre-tax account as the employee and employer contributions.

Does the SECURE 2.0 mandatory Roth catch-up rule apply to sole proprietors?

SECURE 2.0 requires catch-up contributions to be made as Roth contributions for participants with more than $150,000 of W-2 wages from the sponsoring business as of the end of 2025. A sole proprietor who receives no W-2 wages from the business is not subject to that rule. Pre-tax catch-up contributions remain available, and Roth catch-up contributions remain optional.

What income does a sole proprietor need if a day-job 401(k) is already maxed?

The 2026 Solo 401(k) income threshold for a sole proprietor who already made the $24,500 employee deferral at a day job is $376,480.35 of line 31 net income. The employee limit applies to the individual across all plans, so only the employer bucket remains in the Solo 401(k).

The math follows the 20% employer limit. A $72,000 employer contribution requires $360,000 of self-employment compensation, because 20% of $360,000 equals $72,000.

“Well, the answer is right here on our screen. $376,480.35 on line 31 less one half of self-employment tax is going to give them $360,000 of self-employment compensation and then justify that $72,000 employer pre-tax contribution.”

— George Blower, Retirement Accounts Attorney
(20:26 in the webinar)

How does the 403(b) exception change the math?

The 403(b) exception aggregates a day-job 403(b) with the Solo 401(k) under one $72,000 overall limit. Typically, the employer contribution limit applies per plan, so a maxed day-job 401(k) does not reduce Solo 401(k) employer contributions.

“But if that day job plan is a 403(b), then you have to consider the 403(b) exception where all the contributions to the 403(b) together with any contributions that you want to make to the Solo 401(k), the sum cannot exceed the overall limit of $72,000.”

— George Blower, Retirement Accounts Attorney
(21:27 in the webinar)

Example: A participant contributes $24,500 to a day-job 403(b) with no employer contribution. That $24,500 reduces the Solo 401(k) employer contribution capacity by $24,500 under the 403(b) exception. The same $24,500 deferral to a day-job 401(k) would not reduce it.

What income is needed for a Mega Backdoor Roth in 2026?

The 2026 Mega Backdoor Roth income threshold for a sole proprietor under age 50 is $77,473.32 of line 31 net income. That income justifies a $72,000 voluntary after tax contribution, assuming no other Solo 401(k) or 403(b) contributions.

“… unlike the employer contribution limit, which is a percentage of your self-employment compensation, when you make a Mega Backdoor Roth contribution, you can contribute 100% of your self-employment compensation as a voluntary after tax contribution up to the overall limit.”

— George Blower, Retirement Accounts Attorney
(22:42 in the webinar)

Mega backdoor Roth thresholds by age

  • Under age 50: $77,473.32 of line 31 net income justifies $72,000.
  • Ages 50 to 59, or 64 and older: $86,081.46 of line 31 net income justifies $80,000, which is $72,000 after tax plus an $8,000 catch-up.
  • Ages 60 to 63: $89,578.52 of line 31 net income justifies $83,250, which is $72,000 after tax plus an $11,250 super catch-up.

The catch-up amount is made as a direct Roth contribution. It is not made to the after-tax account and later transferred.

How is the Mega Backdoor Roth transferred and reported?

The Mega Backdoor Roth procedure is unchanged for 2026. The first step, a voluntary after tax contribution, is not reportable. The second step, a transfer to a new or existing Roth IRA or a Roth Solo 401(k), is reportable on Form 1099-R.

Info: My Solo 401k Financial prepares the Form 1099-R at no additional charge when the client submits its online form on time. For the full procedure, see Mega Backdoor Roth using a Solo 401(k) plan.

When must a Solo 401(k) be established and funded for 2026?

A 2026 Solo 401(k) must be established by the end of 2026 to preserve the ability to make all contribution types for 2026. A live attendee asked about the dates, and the webinar answered directly.

“If I set up an LLC and create the Solo 401(k), what are the dates to contribute pre-tax employer and employee contributions?”

— Live attendee question, read aloud by George Blower, Retirement Accounts Attorney
(27:12 in the webinar)

“… as long as the plan is established, in other words, you sign up with My Solo 401k Financial by the end of the year, then that’ll preserve the ability to make all types of contributions for 2026 by your 2026 business tax return deadline, including any timely filed extension.”

— George Blower, Retirement Accounts Attorney
(27:18 in the webinar)

Contributions for 2026 can therefore be made as late as the 2026 business tax return deadline, including any timely filed extension, which may fall in 2027. My Solo 401k Financial prepares plan establishment documents within the same business day.

Frequently asked questions about the 2026 Solo 401(k) income thresholds

Does the $72,000 Solo 401(k) limit include the $24,500 employee contribution?

Yes. The 2026 Solo 401(k) overall limit of $72,000 includes the $24,500 employee contribution when it is made to the Solo 401(k) or to a 403(b). An employee contribution to an unrelated employer’s 401(k) does not reduce the Solo 401(k) employer or voluntary after tax limits, if the self-employment income supports them.

Can I have a Solo 401(k) if I already have a W-2 job with a 401(k)?

Yes. A Solo 401(k) is available alongside a W-2 job when no employees work for any business owned by the individual or a spouse. Contribution capacity depends on the side business’s self-employment income, not W-2 wages. The employee deferral limit applies across all plans, while the employer limit applies per plan, subject to the 403(b) exception.

Does the SECURE 2.0 mandatory Roth catch-up rule apply to sole proprietors?

No, not to a sole proprietor who receives no W-2 wages from the business that sponsors the Solo 401(k). SECURE 2.0 requires Roth catch-up contributions for participants with more than $150,000 of W-2 wages from the sponsoring business as of the end of 2025. A sole proprietor may still choose Roth catch-up contributions voluntarily.

Can investment income or day-job wages justify Solo 401(k) contributions?

No. Only self-employment income justifies Solo 401(k) contributions. W-2 wages from a day job, gross business revenue before expenses, and investment income such as Schedule E income do not count. The measure is Schedule C line 31 net income less one half of the self-employment tax.

Do Mega Backdoor Roth contributions have a Form 1099-R reporting step?

Yes, at the second step. Making the voluntary after tax contribution is not reportable. Transferring the money to a Roth IRA or Roth Solo 401(k) account is reportable on Form 1099-R. My Solo 401k Financial prepares the Form 1099-R at no additional charge when the client submits its online form on time.

This article is based on the live webinar hosted by My Solo 401k Financial.

Ready to open a Solo 401(k) for 2026?

My Solo 401k Financial prepares plan establishment documents within the same business day.

Open a Solo 401(k) account

Educational purposes only: This article is provided for educational purposes only. The content should not be construed as tax, legal, or investment advice, nor as a solicitation. Consult a tax attorney and financial professional before making an investment decision.
Solo 401k for 1099 Contractors: Only 1099-NEC Income Qualifies

Solo 401k With 1099 Income: No LLC Needed, Up to $72,000 for 2026

By Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial · Published

Direct answer: A self-employed contractor can open a Solo 401k with 1099 income when that income is reported on Form 1099-NEC for services the contractor actually performed. No LLC or corporation is required. Contributions are calculated from net profit on Schedule C, line 31, reduced by one-half of self-employment tax. Interest (1099-INT), dividends (1099-DIV), and retirement distributions (1099-R) are not earned income and do not qualify.

Key Takeaways

  • Form 1099-NEC income from services you personally perform qualifies a sole proprietor for a Solo 401k without forming an LLC or corporation.
  • Solo 401k contributions for a 1099 contractor start from Schedule C, line 31 (net profit), reduced by one-half of self-employment tax.
  • Income reported on Form 1099-INT, Form 1099-DIV, or Form 1099-R is not earned income and cannot support Solo 401k contributions.
  • For 2026, the overall Solo 401k limit is $72,000 under age 50, $80,000 with the $8,000 catch-up, and $83,250 for ages 60 through 63.
  • A contractor who maxes a $72,000 day-job 401k can still put up to $72,000 into a Solo 401k through employer and voluntary after-tax contributions, if self-employment earnings support it.
  • A Solo 401k is unavailable if a non-owner W-2 employee works 1,000 or more hours a year in the business; a working spouse is the exception.
  • Someone who is not self-employed cannot open a Solo 401k just to consolidate IRAs or isolate pre-tax IRA money for a backdoor Roth IRA.

Status: As of , the Solo 401k eligibility rules and 2026 contribution limits described here are current law; the 2027 limits had not yet been announced when the webinar was recorded.

Full webinar replay: Solo 401k with 1099 income — eligibility, Schedule C math, and 2026 limits, presented by My Solo 401k Financial.

Can you open a Solo 401k with 1099 income?

A Solo 401k with 1099 income is available to any sole proprietor who performs services and receives Form 1099-NEC pay. The 1099-NEC reports non-employee compensation, which the IRS treats as self-employment income. A formal entity is not required. The sole proprietor files Schedule C with the personal Form 1040 return, and that filing is enough.

What determines eligibility is the underlying activity. You must be doing the actual work, not collecting investment returns. An IT consultant paid by clients on 1099-NEC forms meets that test. For a broader look at how the plan works, see our overview of Solo 401k plan rules and features.

“So as you can see, you don’t have to have a formal entity type to qualify for a Solo 401k plan. So whether you are a 1099-NEC contractor or you have your own formal entity such as an LLC, an S corporation or partnership, for example, what matters is the underlying activity.”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial
(1:51 in the webinar)

Who counts as a 1099 contractor for Solo 401k purposes?

Solo 401k eligibility through 1099 income covers a wide range of independent workers. The webinar named freelancers, consultants, and gig workers such as Uber or Lyft drivers. Real estate agents earning qualifying commissions also fit. Attorneys, accountants, and other professionals may receive 1099-NEC pay directly instead of operating through an LLC.

“Now, again, it has to be Form 1099-NEC, which stands for non-employee compensation. That means you’re a contractor.”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial
(2:58 in the webinar)

The employee rule for an owner-only business

A Solo 401k is built for an owner-only business. The business cannot employ a non-owner W-2 employee who works 1,000 hours or more in a year. Most 1099 contractors have no employees, so the rule rarely blocks them. A spouse who works in the business is the exception and does not disqualify the plan.

Important: SECURE 2.0 added long-term part-time employee rules that can bring in employees working fewer than 1,000 hours. Confirm your employee situation with your plan provider before hiring anyone.

Which 1099 forms count as earned income for a Solo 401k?

Solo 401k eligibility requires earned income from self-employment activity. The IRS requires earned income both to open the plan and to make contributions. Only Form 1099-NEC meets that standard among the common 1099 forms. Forms reporting interest, dividends, or retirement distributions reflect investment or plan money, not compensation for work.

Which 1099 forms qualify as earned income for Solo 401k eligibility and contributions
Form What it reports Counts for Solo 401k?
Form 1099-NEC Non-employee compensation for services performed Yes — earned income
Form 1099-INT Interest from savings accounts or CDs No — investment income
Form 1099-DIV Dividends from personal stock holdings No — passive investment income
Form 1099-R (distribution, including RMDs) Money paid out of a retirement account No — a distribution, not earned income
Form 1099-R, code G (direct rollover) Funds moved directly between retirement accounts No — not a contribution source

Summary: Only Form 1099-NEC income counts toward Solo 401k eligibility and contributions; 1099-INT, 1099-DIV, and 1099-R amounts do not.

“That’s not considered earned income. That’s investment income. It’s passive, so it does not qualify for both opening a Solo 401k or for making Solo 401k contributions.”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial
(10:20 in the webinar)

Why a required minimum distribution cannot be re-contributed

A required minimum distribution from a Solo 401k cannot be deposited back into the Solo 401k or any other retirement account. The distribution is reported on Form 1099-R and is not earned income. A $10,000 RMD stays out of the plan. Personal stock and securities gains are excluded for the same reason.

How are Solo 401k contributions calculated from 1099-NEC income?

Solo 401k contributions for a 1099 contractor are calculated from Schedule C, line 31. Line 31 shows net profit after all business expenses. From that figure, subtract one-half of self-employment tax. The result drives both the employee and employer contribution calculations.

“And then the calculation would be based on line 31 of that Schedule C, which again is the tax return that you attach to your personal Form 1040 return when you are a contractor.”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial
(7:55 in the webinar)

Example: A consultant receives a separate Form 1099-NEC from each of three clients.

  1. Add the three 1099-NEC amounts to get total self-employment income.
  2. Report the total on Schedule C and subtract business expenses.
  3. Take the net profit on line 31 and subtract one-half of self-employment tax.
  4. Use the result to calculate employee and employer Solo 401k contributions.

When an LLC receives the 1099-NEC

A single-member LLC taxed as a sole proprietorship may receive the 1099-NEC in the LLC’s name. The Solo 401k calculation is unchanged. The income still flows to Schedule C, and line 31 remains the starting figure. An LLC taxed as an S corporation is different: its Solo 401k contributions are based on W-2 wages.

What are the 2026 Solo 401k contribution limits?

The 2026 Solo 401k contribution limit is $72,000 for participants under age 50. Within that total, the employee deferral is capped at $24,500. Participants age 50 or older can add an $8,000 catch-up. Participants ages 60 through 63 instead qualify for an $11,250 super catch-up under SECURE 2.0.

“But for 2026, the overall Solo 401k contribution limit is $72,000 for those who are under age 50.”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial
(15:10 in the webinar)
2026 Solo 401k contribution limits by contribution type and age
Contribution type Who it applies to 2026 amount
Employee deferral All participants $24,500
Regular catch-up Age 50 or older (except 60–63) $8,000
Super catch-up Ages 60 through 63 $11,250
Overall limit Under age 50 $72,000
Overall limit with regular catch-up Age 50 or older (except 60–63) $80,000
Overall limit with super catch-up Ages 60 through 63 $83,250

Summary: The 2026 Solo 401k overall limit is $72,000, rising to $80,000 with the regular catch-up and $83,250 with the ages 60–63 super catch-up.

A participant cannot take both catch-ups in the same year. Someone over age 63 reverts to the regular $8,000 catch-up. The webinar noted that 2026 contributions can be made until the 2027 business tax return due date, plus extensions.

Important: For sole proprietors, the timing of the employee deferral election can differ from the deposit deadline. Confirm the election date for your situation before year-end. [VERIFY: firm position on sole proprietor deferral election timing vs. deposit deadline]

Can you have a Solo 401k and a day-job 401k at the same time?

A Solo 401k can run alongside a full-time employer’s 401k when the participant also has side 1099-NEC income. Employee deferrals are aggregated across both plans, so the $24,500 cap is shared. Employer profit-sharing and voluntary after-tax contributions are not aggregated. Each unrelated employer’s plan carries its own $72,000 overall limit.

The webinar used “Johnny” as an example. Johnny works for Microsoft and maxes his $72,000 Microsoft 401k for 2026. Johnny also does contract work on the side and receives 1099-NEC income. He can still open a Solo 401k for that contracting business.

“So my Johnny example, if Johnny has enough earned income from self-employment activity, he can contribute another $72,000 to a Solo 401k plan as a voluntary after-tax Solo 401k contribution.”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial
(22:17 in the webinar)

Johnny’s after-tax dollars can then be converted to Roth, a strategy known as the Mega Backdoor Roth using a Solo 401k. Johnny could also split the amount between employer profit-sharing and after-tax contributions. Combined, those Solo 401k contributions still cannot exceed $72,000.

Can you open a Solo 401k only to roll over IRAs?

A Solo 401k cannot be opened solely for rollovers by someone who is not self-employed. Self-employment is required both to open the plan and to keep it. Annual contributions are optional, because a Solo 401k is a defined contribution plan. Rollovers have no minimum and do not reduce annual contribution limits.

“So if you don’t meet those eligibility requirements, then no, you’re not gonna be able to transfer IRAs, former employer plans, or utilize the solo to isolate your non-deductible IRA funds…”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial
(13:53 in the webinar)

Can a spouse or partner join a Solo 401k?

A spouse or partner can be added to a Solo 401k in two different roles. An attendee asked about timing during the live session.

“When is the best time for your partner to join your 401k after she leaves her current employment…?”

— Attendee question, read live by Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial
(19:09 in the webinar)

Co-trustee versus participant

A Solo 401k co-trustee signs plan documents such as amendments, distribution requests, and bank or brokerage paperwork. A co-trustee does not need to work in the business. A Solo 401k participant must perform self-employment activity in the same business. A partner’s full-time day job does not block participation.

“And can the LLC pay her services? Can she turn around and add that to her contribution to the Solo 401k plan?”

— Attendee question, read live by Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial
(23:42 in the webinar)

The answer given live was yes, with conditions. The partner must perform self-employment activity in the business. The partner also cannot own a business with full-time employees. Once added, the partner can contribute, roll over IRAs, and take a participant loan. The overall contribution limit applies per participant, not per plan.

Other Solo 401k questions from the live session

Is a Solo 401k a revocable trust?

A Solo 401k is a retirement trust, as are all 401k plans and IRAs. A retirement trust is different from a living trust, land trust, or family trust. A Solo 401k is revocable, meaning it can be amended. Common amendments add a new self-employed business or a new participant.

When can Solo 401k distributions begin?

Solo 401k distributions can begin at normal retirement age, defined in the webinar as 59½ or older. Required minimum distributions from pre-tax funds begin at age 73. The first RMD can be delayed to April 1 of the following year. Delaying means two taxable RMDs in that year.

Solo 401k distributions paid to the participant carry a mandatory 20% federal withholding. The plan must register with the Department of the Treasury and wire that tax. A workaround discussed live is a partial transfer to an IRA first. The transfer is reported on Form 1099-R with code G. IRA distributions are not subject to the mandatory 20% withholding, though income tax is still owed.

Frequently Asked Questions

Can you open a Solo 401k with 1099 income?

Yes, a Solo 401k can be opened with 1099 income reported on Form 1099-NEC. Form 1099-NEC shows non-employee compensation, which means the recipient performed services as an independent contractor. That self-employment income satisfies the earned income requirement. Contractors, freelancers, consultants, and gig workers commonly qualify. Interest, dividend, and retirement distribution forms do not create eligibility.

Do I need an LLC to open a Solo 401k?

No, a Solo 401k does not require an LLC, S corporation, or partnership. A sole proprietor who receives 1099-NEC income and files Schedule C qualifies. What matters is performing actual services, not the legal form of the business. A single-member LLC taxed as a sole proprietorship uses the same Schedule C calculation.

Does 1099-INT or 1099-DIV income count for a Solo 401k?

No, income on Form 1099-INT or Form 1099-DIV does not count for a Solo 401k. Interest from savings accounts or CDs and dividends from personal stock holdings are investment income. Neither is earned income from self-employment. Without 1099-NEC or other self-employment income, these forms cannot support opening a Solo 401k or contributing to one.

How do I calculate Solo 401k contributions from 1099-NEC income?

Solo 401k contributions from 1099-NEC income start with Schedule C, line 31. Add all 1099-NEC amounts, report them on Schedule C, and subtract business expenses. Line 31 shows the resulting net profit. Subtract one-half of self-employment tax from line 31. That figure drives the employee and employer contribution calculations.

Can I have a Solo 401k if I already have a 401k at work?

Yes, a Solo 401k can exist alongside a day-job 401k if you have side self-employment income. Employee deferrals are shared across both plans under one $24,500 cap for 2026. Employer and voluntary after-tax contributions are not shared. A Solo 401k for an unrelated business carries its own $72,000 overall limit, subject to earnings.

What is the Solo 401k contribution limit for 2026?

The 2026 Solo 401k overall contribution limit is $72,000 for participants under age 50. The employee deferral portion is $24,500. Participants age 50 or older can add an $8,000 catch-up, for $80,000 total. Participants ages 60 through 63 can add an $11,250 super catch-up instead, for $83,250 total.

Can I open a Solo 401k just to roll over my IRA if I’m not self-employed?

No, a Solo 401k requires self-employment to open and to maintain the plan. Someone without self-employment activity cannot use a Solo 401k to consolidate IRAs or former employer plans. The same applies to isolating pre-tax IRA funds for a backdoor Roth IRA. Annual contributions are optional, but eligibility is not.

Can my spouse or partner join my Solo 401k?

A spouse or partner can join a Solo 401k as a co-trustee or as a participant. A co-trustee signs plan documents and does not need to work in the business. A participant must perform self-employment activity in the same business. Each participant receives a separate overall contribution limit, because the limit applies per person.

Glossary

Form 1099-NEC
An IRS form reporting non-employee compensation paid to an independent contractor for services performed.
Earned income
Compensation from work performed, including self-employment income; it excludes interest, dividends, and retirement distributions.
Schedule C, line 31
The net profit line on a sole proprietor’s Schedule C, used as the starting figure for Solo 401k contributions.
Owner-only business
A business with no non-owner W-2 employees working 1,000 or more hours a year, other than a spouse.
Voluntary after-tax contribution
A Solo 401k contribution made with after-tax dollars, often converted to Roth as part of a Mega Backdoor Roth.
Super catch-up
A SECURE 2.0 catch-up contribution for participants ages 60 through 63, set at $11,250 for 2026.

This article is based on the [VERIFY: webinar date] live webinar hosted by My Solo 401k Financial. Analysis by Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial.

Ready to open a Solo 401k for your 1099 income?

My Solo 401k Financial sets up the plan, supports Mega Backdoor Roth contributions, and calculates contributions for clients as part of ongoing support.

Open a Solo 401k account

Educational purposes only: This article is for general educational purposes and is not tax, legal, or investment advice. Consult a qualified tax professional or financial advisor about your specific situation.


S Corp Solo 401(k) W-2 Salary Needed to Max Out in 2026

S Corp Solo 401(k): $190,000 W-2 Maxes Pre-Tax, $72,000 Maxes Roth

Direct answer

An S Corp Solo 401(k) owner under age 50 needs $190,000 of W-2 wages to make the full $72,000 pre-tax contribution for 2026. The requirement rises to $288,000 when a day-job plan has already used the $24,500 employee limit. Only $72,000 of W-2 wages is needed to contribute $72,000 as voluntary after-tax money that is converted to Roth.

Key takeaways: S Corp Solo 401(k) W-2 salary requirements for 2026

  • The 2026 overall contribution limit for an S Corp Solo 401(k) is $72,000, combining employee, employer, and voluntary after-tax contributions.
  • The 2026 employee deferral limit is $24,500 per person across all plans, so a maxed-out day-job 401(k) leaves no employee deferral room.
  • The employer contribution is capped at 25% of S corporation W-2 wages, so $190,000 of W-2 wages supports a $47,500 employer contribution.
  • An S Corp Solo 401(k) owner with no other plan needs $190,000 of W-2 wages for the $72,000 pre-tax maximum, or $288,000 if a day-job plan used the employee limit.
  • A plan that allows voluntary after-tax contributions needs only $72,000 of W-2 wages to contribute $72,000, which can then be converted to Roth.
  • The 2026 catch-up contribution is $8,000 for ages 50 to 59 and 64 and older, and $11,250 for ages 60 to 63, raising totals to $80,000 and $83,250.
  • Form 1099-R reports the after-tax-to-Roth transfer, while the after-tax contribution itself does not appear on the W-2 or the tax returns.

Video: live My Solo 401k Financial webinar on the S Corp Solo 401(k) W-2 salary needed to max out 2026 contributions.

How much W-2 salary do I need to max out an S Corp Solo 401(k) in 2026?

An S Corp Solo 401(k) requires between $72,000 and $288,000 of 2026 W-2 wages to reach its maximum. The amount depends on the contribution type and on any day-job plan.

2026 W-2 wages required by S Corp Solo 401(k) strategy
Strategy Total contribution W-2 wages required How the contribution splits
Pre-tax maximum, no other plan, under age 50 $72,000 $190,000 $24,500 employee + $47,500 employer
Pre-tax maximum, no other plan, ages 50–59 or 64+ $80,000 $190,000 $32,500 employee + $47,500 employer
Pre-tax maximum, no other plan, ages 60–63 $83,250 $190,000 $35,750 employee + $47,500 employer
Pre-tax maximum, day-job plan already maxed $72,000 $288,000 $72,000 employer only
Roth maximum, under age 50 $72,000 $72,000 $72,000 after-tax, then converted to Roth
Roth maximum, ages 50–59 or 64+ $80,000 $80,000 $72,000 after-tax + $8,000 catch-up straight to Roth
Roth maximum, ages 60–63 $83,250 $83,250 $72,000 after-tax + $11,250 super catch-up straight to Roth

What are the 2026 S Corp Solo 401(k) contribution limits?

The S Corp Solo 401(k) has three 2026 limits that work together: a $24,500 employee deferral limit, a 25% employer contribution limit, and a $72,000 overall limit.

Employee deferral limit: $24,500

The S Corp Solo 401(k) employee deferral limit for 2026 is $24,500, or 100% of W-2 wages when wages are lower. The limit belongs to the person, not the plan, so deferrals to a day-job 401(k) reduce the room left.

“… the employee contribution limit is $24,500. That’s 100% of your W-2 wages from your self-employed business taxed as an S corporation.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial (5:49 in the webinar)

Employer contribution limit: 25% of W-2 wages

The S Corp Solo 401(k) employer contribution limit is 25% of the owner’s W-2 wages from the S corporation. Wages for this purpose equal box one of the W-2 plus any pre-tax deferrals reported in box 12.

Overall limit and catch-up: $72,000 to $83,250

The S Corp Solo 401(k) overall limit for 2026 is $72,000, counting employee, employer, and voluntary after-tax contribution dollars together. Owners aged 50 to 59 or 64 and older at the end of 2026 can add an $8,000 catch-up contribution, for $80,000 in total. Owners aged 60 to 63 can add an $11,250 super catch-up instead, for $83,250 in total.

Each catch-up is available only when the owner has not used it in another plan, such as a day-job plan, and has the income to support it.

2026 S Corp Solo 401(k) limits and where each limit applies
Limit 2026 amount Where the limit applies
Employee deferral $24,500 Person level: shared across every plan the owner participates in
Catch-up, ages 50–59 and 64+ $8,000 Person level: unavailable if already used in another plan
Super catch-up, ages 60–63 $11,250 Person level: unavailable if already used in another plan
Employer contribution 25% of W-2 wages Plan level: based on W-2 wages from the S corporation
Overall limit $72,000 Plan level: a day-job 403(b) is aggregated with it

What counts as W-2 income for an S Corp Solo 401(k)?

An S Corp Solo 401(k) counts only W-2 wages from the S corporation as income for contribution purposes. Schedule K-1 profit never counts, and no owner can save more than the wages earned.

“… your income when your business is taxed as an S corporation is really the W-2 wages that you receive from the S corporation. So it’s really box one of the W-2 plus any pre-tax elective deferrals not in box one but over in box 12.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial (7:32 in the webinar)

Wages reported in box one of the W-2 can be used to justify contributions. An owner who has already received W-2 wages does not need to run another payroll to justify contributions.

How much W-2 salary does an S Corp Solo 401(k) need for the pre-tax maximum with no day job?

An S Corp Solo 401(k) owner under age 50 with no other plan needs $190,000 of 2026 W-2 wages to contribute the full $72,000 pre-tax. The contribution splits into a $24,500 employee deferral and a $47,500 employer contribution.

Example: With $190,000 of W-2 wages, the $24,500 deferral lowers box one of the W-2 to $165,500 and appears in box 12. The employer calculation adds the deferral back: $190,000 times 25% equals $47,500. The total contribution is $72,000.

“So, it’s box one plus box 12, that’s $190,000 times 25%. The employer contribution limit for an S corporation is 25% of the W-2 wages from the S corporation. So that yields 47,500, bringing their total contribution amount to $72,000.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial (10:20 in the webinar)

The S Corp Solo 401(k) employee deferral lowers box one of the W-2, which produces the income tax reduction. The $47,500 employer contribution is reported on the S corporation tax return and flows through the K-1 to the owner.

Ages 50 to 59 or 64 and older: $80,000

An S Corp Solo 401(k) owner aged 50 to 59 or 64 and older with $190,000 of W-2 wages and no other plan can contribute $80,000. The total is $32,500 of employee deferrals, which includes the $8,000 catch-up, plus the $47,500 employer contribution.

Ages 60 to 63: $83,250

An S Corp Solo 401(k) owner aged 60 to 63 at the end of 2026 can add the $11,250 super catch-up. Employee deferrals reach $35,750, and the $47,500 employer contribution brings the total to $83,250.

The $150,000 Roth catch-up rule

Important: An S Corp Solo 401(k) owner whose S corporation paid more than $150,000 of Social Security wages (W-2 box 3) in 2025 must make 2026 catch-up contributions as Roth. The catch-up amount can still be contributed, but the catch-up portion goes in as Roth instead of pre-tax. Owners below the threshold can choose Roth or pre-tax. SECURE 2.0 section 603 created the rule, and it as a trap for owners seeking pre-tax deductions.

How much W-2 salary does an S Corp Solo 401(k) need if a day-job plan is already maxed out?

An S Corp Solo 401(k) owner who already maxed out a day-job 401(k) needs $288,000 of 2026 W-2 wages to make a $72,000 pre-tax contribution. The employee deferral limit applies to the person across all plans, so only the employer contribution remains.

The employer contribution is 25% of W-2 wages. A $72,000 employer contribution therefore requires $288,000 of W-2 wages.

“They would need $288,000 of W-2 wages from the business taxed as an S corp because 25% of $288,000 is $72,000, which again would be a pre-tax contribution to reduce their taxable income for 2026.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial (14:32 in the webinar)
Important: The employee deferral bucket fills only once per person. A maxed-out day-job plan leaves no employee deferral room in the S Corp Solo 401(k).

How does the Mega Backdoor Roth work in an S Corp Solo 401(k)?

The Mega Backdoor Roth in an S Corp Solo 401(k) is a voluntary after-tax contribution followed by a transfer to the Roth account. For a deeper walkthrough, see this guide to the Mega Backdoor Roth using a Solo 401(k) plan.

The plan document must allow voluntary after-tax contributions. Discount brokerage plans do not allow them, while the My Solo 401k Financial plan does.

The S Corp Solo 401(k) process has two steps. First, the owner contributes to a separate after-tax account. Second, the owner moves the money to the Roth account, where it has potential for tax-free growth.

What gets reported

The after-tax contribution to an S Corp Solo 401(k) does not need to be reported on the personal return, the business return, or the W-2. The after-tax-to-Roth transfer is reportable on Form 1099-R. My Solo 401k Financial prepares that Form 1099-R at no additional charge when notified in a timely way through the form on its website.

Roth Solo 401(k) account or Roth IRA

Under the My Solo 401k Financial plan, after-tax money can move to either a Roth IRA or a Roth Solo 401(k). An owner who wants a Roth 401(k) loan option or alternative investments needs at least two accounts: an after-tax account and a Roth account. Learn more about the Solo 401(k) plan on the My Solo 401k Financial site.

How much W-2 salary does an S Corp Solo 401(k) need for the Roth maximum?

An S Corp Solo 401(k) owner can reach a $72,000 Roth balance with only $72,000 of W-2 wages. Voluntary after-tax contributions allow 100% of wages, dollar for dollar, up to the overall limit, so the owner can skip employee and employer contributions entirely.

“… as long as they have box one W-2 wages of $72,000, they can contribute the full $72,000 as an after tax contribution to the after tax solo 401k account and then convert the money to the Roth account.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial (16:07 in the webinar)

Day-job plans do not reduce the voluntary after-tax limit

The voluntary after-tax limit of an S Corp Solo 401(k) applies at the plan level, so a maxed-out day-job 401(k) does not reduce it. The owner still needs at least $72,000 of W-2 wages from the S corporation.

“… unlike the employee limit that applies at the employee level, the voluntary after tax contribution limit is not reduced by contributions made to a day job 401k plan. It applies at the plan level.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial (16:47 in the webinar)

There is an important exception. Contributions to a day-job 403(b), whether employee or employer, are aggregated with S Corp Solo 401(k) contributions, and the sum cannot exceed the overall limit.

Roth maximum with catch-up contributions

An S Corp Solo 401(k) owner aged 50 to 59 or 64 and older needs $80,000 of W-2 wages to add the $8,000 catch-up. An owner aged 60 to 63 needs $83,250 to add the $11,250 super catch-up. Catch-up dollars skip the after-tax bucket and go straight to Roth, so the owner ends with $80,000 or $83,250 in the Roth account.

Can an S Corp Solo 401(k) restated in October 2026 still receive 2026 mega backdoor Roth contributions?

An owner who restates a prior 401(k) into an S Corp Solo 401(k) in October 2026 can still make 2026 Mega Backdoor Roth contributions when unused overall-limit capacity remains.

Attendee question

“I’ve already contributed employee 401k and employer 401k contributions to my prior 401k plan. Can I restate with my solo 401k in October 2026 and still contribute after tax Mega Backdoor Roth for 2026?”

— Attendee question from G, submitted by chat and read aloud in the webinar by George Blower, Retirement Accounts Attorney, My Solo 401k Financial (21:22 in the webinar)

Contributions already made to the prior plan cannot be unwound, and they count against the limits. Any remaining capacity needs W-2 wages to justify it.

The after-tax contributions can be made by the business tax return deadline, including extensions. The 2026 S corporation deadline is , or with a timely extension. The plan must be established by the end of the year.

After the application and payment are submitted, My Solo 401k Financial prepares restatement documents within the same business day. Moving assets from the prior plan requires a separate transfer form.

S Corp Solo 401(k) W-2 salary FAQs

How much W-2 income do I need for the $72,000 pre-tax S Corp Solo 401(k) contribution?

An S Corp Solo 401(k) owner under age 50 with no other plan needs $190,000 of 2026 W-2 wages to contribute $72,000 pre-tax. The contribution splits into a $24,500 employee deferral and a $47,500 employer contribution, which equals 25% of $190,000. Box one of the W-2 falls to $165,500 because the deferral is reported in box 12.

How much W-2 salary do I need for an S Corp Solo 401(k) if I already max out a day-job 401(k)?

An S Corp Solo 401(k) owner who already maxed out a day-job 401(k) needs $288,000 of 2026 W-2 wages for a $72,000 pre-tax contribution. The employee deferral limit is shared across all plans, so only the employer contribution remains. Employer contributions equal 25% of W-2 wages, and 25% of $288,000 is $72,000.

Can I contribute $72,000 to a Solo 401(k) with only $72,000 of S corp W-2 wages?

Yes, if the S Corp Solo 401(k) plan document allows voluntary after-tax contributions. The owner contributes 100% of W-2 wages dollar for dollar up to $72,000 as voluntary after-tax money, then converts it to the Roth account. Discount brokerage plans do not allow voluntary after-tax contributions.

Does a day-job 401(k) reduce how much I can contribute after-tax to my S Corp Solo 401(k)?

A day-job 401(k) does not reduce the voluntary after-tax limit of an S Corp Solo 401(k). That limit applies at the plan level, not the person level. The exception is a day-job 403(b), whose employee and employer contributions are aggregated with S Corp Solo 401(k) contributions under the $72,000 overall limit.

Can I use K-1 profit to justify S Corp Solo 401(k) contributions?

No. An S Corp Solo 401(k) counts only W-2 wages from the S corporation as earned income. The base is box one of the W-2 plus any pre-tax elective deferrals reported in box 12. Schedule K-1 profit does not support contributions, and no owner can contribute more than the W-2 wages earned.

Is the Mega Backdoor Roth conversion in an S Corp Solo 401(k) reported to the IRS?

The transfer from the after-tax account to the Roth account in an S Corp Solo 401(k) is reportable on Form 1099-R. The after-tax contribution itself does not need to be reported on the personal return, the business return, or the W-2. Later transfers of like funds between bank and brokerage accounts are not reportable.

Can I restate to an S Corp Solo 401(k) in October 2026 and still make 2026 mega backdoor Roth contributions?

Yes, when overall-limit capacity remains. An S Corp Solo 401(k) restatement in October 2026 cannot unwind contributions already made to the prior plan. Remaining capacity can fund voluntary after-tax contributions if W-2 wages justify them. Those contributions are due by the business tax return deadline, including extensions.

Do S corp owners have to make Roth catch-up contributions to an S Corp Solo 401(k)?

An S Corp Solo 401(k) owner must make catch-up contributions as Roth when the S corporation paid more than $150,000 of Social Security wages in 2025. Below the threshold, the owner can choose Roth or pre-tax catch-up contributions. The 2026 catch-up is $8,000, or $11,250 for ages 60 to 63.

This article is based on the  live webinar hosted by My Solo 401k Financial. Analysis by George Blower, Retirement Accounts Attorney, My Solo 401k Financial.

My Solo 401k Financial prepares plan documents that allow voluntary after-tax contributions and the Mega Backdoor Roth. Open a Solo 401(k) account with My Solo 401k Financial to get started.


Solo 401k Business Entity Change: Same $72,000 Limit, Different Math

Solo 401k Business Entity Change: Same $72,000 Limit, Different Math

Direct Answer

A Solo 401k business entity change does not require a new plan. When a sole proprietorship becomes an LLC taxed as an S corporation, the new entity becomes the plan sponsor and the existing plan is amended (i.e. restated). The plan name, plan EIN, accounts, and investments stay in place. Contribution limits stay the same, but the calculation shifts from Schedule C income to W-2 wages.

Key Takeaways

  • A Solo 401k business entity change does not create a new plan. The existing plan is amended to list the new plan sponsor, such as an LLC taxed as an S corporation.
  • The Solo 401k plan name and plan EIN stay the same after an entity change, even when the business obtains a separate business EIN.
  • A Solo 401k plan that files Form 5500-EZ, an informational return filed when plan value exceeds $250,000, must list the new entity and its new EIN on later filings.
  • A sole proprietor calculates Solo 401k contributions from Schedule C line 31 net income less one-half of self-employment tax, while an S corporation owner uses W-2 wages.
  • For 2026, the Solo 401k employee deferral limit is $24,500 and the overall limit is $72,000, plus eligible catch-up contributions.
  • A Solo 401k business entity change involves one plan amendment and zero account transfers; brokerage custodians may ask for a copy of the amendment showing the new plan sponsor.

Video: live webinar on Solo 401k business entity change hosted by My Solo 401k Financial.

What happens to my Solo 401k plan if I change my business entity from a sole proprietor to an S corp?

A Solo 401k business entity change leaves the existing plan in place. A business moving from a sole proprietorship to an LLC taxed as an S corporation does not need a new plan. The plan documents are updated to list the new entity as plan sponsor.

A Solo 401k plan can be established without a legal entity. A sole proprietorship can adopt a plan and later graduate to an LLC taxed as an S corporation. The original plan documents list the business as a sole proprietorship, so the documents need an amendment once the LLC taxed as an S corporation operates the business.

“So the answer is no. It’s not a new plan. You really just update the plan documents. It’s a document update.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial (3:39 in the webinar)

“So you’re not shutting down the existing plan and starting a new plan. You’re really just amending, or what they call restating, that existing plan to show that new entity…”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial (5:02 in the webinar)

Which entity changes follow the same reasoning?

A Solo 401k business entity change can run in several directions: such as an S corporation becoming a sole proprietorship and an LLC taxed as a sole proprietorship becoming a partnership. Many of the same concepts apply, and the webinar used the sole proprietorship-to-S corporation example to explain them.

What stays the same and what changes in a Solo 401k business entity change?

Comparison of a Solo 401k before and after a change from a sole proprietorship to an LLC taxed as an S corporation
Entity Plan sponsor named in plan documents Income basis for contributions Form 5500-EZ sponsor and EIN Plan name and plan EIN
Sole proprietorship (before the change) The sole proprietorship Schedule C net income less one-half of self-employment tax The sole proprietorship and its EIN As originally established
LLC taxed as an S corporation (after the change) The LLC taxed as an S corporation W-2 wages The S corporation and its new business EIN, linked to the prior name and EIN Unchanged

In summary, a Solo 401k business entity change replaces the plan sponsor, the contribution income basis, and the Form 5500-EZ sponsor details, while the plan name and plan EIN stay unchanged.

Does a Solo 401k business entity change affect the plan EIN and the business EIN?

A Solo 401k business entity change keeps the plan EIN unchanged, and the plan EIN is separate from the business EIN. A sole proprietor may never have needed a business EIN. The tax advisor may have used a Social Security number instead.

An S corporation needs its own business EIN, which is separate and distinct from the EIN used for the Solo 401k plan. The plan EIN is the number used for Solo 401k accounts and investments. An investment provider, such as a private placement sponsor, asks for the plan EIN.

“So the plan is going to continue. So the name of the plan is going to stay the same. The EIN number of the plan is going to stay the same, but maybe your business EIN changes.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial (6:29 in the webinar)

How does a Solo 401k business entity change affect Form 5500-EZ?

A Solo 401k business entity change affects Form 5500-EZ only when the plan has been filing the form. Form 5500-EZ is an informational tax return filed by the plan sponsor when plan value exceeds $250,000. The sponsor is the business entity, so later filings must show the new entity.

“That 5500-EZ would have listed your sole proprietorship as the plan sponsor, but going forward, it’s going to need to … list your S corporation.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial (7:11 in the webinar)

How does Form 5500-EZ link the prior name and EIN?

Form 5500-EZ includes a section where the filer lists the name and EIN used in the past. Listing the prior name and EIN lets the IRS connect the earlier and later filings.

How does a Solo 401k business entity change affect contribution calculations?

A Solo 401k business entity change does not alter the contribution limits or the contribution types. The plan still offers employee, employer, and voluntary after-tax contributions, including the Mega Backdoor Roth strategy with a Solo 401k plan. The income used to calculate each contribution is what changes.

How does a sole proprietor calculate Solo 401k contributions?

A sole proprietor reports earned self-employment income on Schedule C of Form 1040. The calculation starts with net income on line 31 of Schedule C, less one-half of self-employment tax. An employer contribution can be 20% of that figure.

Employee deferrals can equal 100% of that figure, up to the employee limit. Voluntary after-tax contributions can equal 100% of that figure, up to the overall limit. The three contribution types combined cannot exceed the lesser of that self-employment compensation or the overall limit of $72,000.

How does an S corporation owner calculate Solo 401k contributions?

After the business is taxed as an S corporation, the ability to contribute is based on W-2 wages. This does not mean a person can contribute more. Different numbers determine how much goes into each contribution type, and the totals are aggregated to stay within the applicable limits.

“So it doesn’t impact how much you can contribute in terms of the limits, but it impacts how you determine how much you can contribute. Same plan, different math, in other words.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial (9:34 in the webinar)

Example: A business operates as a sole proprietorship in the first half of a year and as an LLC taxed as an S corporation in the second half. Contributions for the first half are based on Schedule C income. Contributions for the second half are based on W-2 wages. Each period is calculated separately, but one deferral limit and one combined base cap still apply.

What are the 2026 Solo 401k contribution limits?

The 2026 Solo 401k limits do not change with the entity type. The employee limit is $24,500. Tthe catch-up contribution is $8,000, and the super catch-up for ages 60 to 63 replaces it.

“If you’re age 60 to 63 as of the end of 2026, you can make a super catch-up contribution of $11,250 instead of the $8,000. And then your overall limit for 2026 is $72,000 or more if you’re eligible to make those catch-up contributions.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial (11:31 in the webinar)
2026 Solo 401k contribution amounts and the effect of a business entity change
Contribution type 2026 amount or rate Effect of an entity change
Employee deferral $24,500 Limit unchanged
Catch-up contribution (age 50 or older) $8,000 Limit unchanged
Super catch-up contribution (ages 60 to 63 as of the end of 2026) $11,250 instead of $8,000 Limit unchanged
Overall limit $72,000, or more with eligible catch-up contributions Limit unchanged
Employer contribution (sole proprietor) 20% of Schedule C net income less one-half of self-employment tax Income basis changes to W-2 wages after the S corporation change

Do Solo 401k accounts need to move after a Solo 401k business entity change?

A Solo 401k business entity change does not require moving accounts or selling investments. The change replaces only the plan sponsor, so the plan continues with the same name and the same plan EIN. Existing accounts stay in place.

Important: A custodian may need notice of the entity change. Some custodians, such as brokerage firms, match the plan sponsor on their system to the name on the external account that funds contributions. A business that switches from funding contributions from a personal account to an S corporation account may need to tell the brokerage firm and provide a copy of the amendment.

My Solo 401k Financial offers a one-time service for a one-time fee to process the amendment. The amendment is a full restatement of the documents that shows the new business entity. The investments, the account title, and the plan EIN are unaffected.

Solo 401k business entity change: frequently asked questions

Do I need a new Solo 401k plan if I change my business entity?

No. A Solo 401k business entity change does not require a new plan. The existing plan is amended or restated so the new entity, such as an LLC taxed as an S corporation, appears as the plan sponsor. The plan name, plan EIN, accounts, and investments continue, so the business updates documents rather than shutting down and starting over.

Does the Solo 401k plan EIN change when my business entity changes?

No. The Solo 401k plan EIN stays the same after a business entity change, and the plan name stays the same. The business may obtain a new business EIN, which is separate from the plan EIN. The plan EIN remains the number given to investment providers, such as a private placement sponsor.

Do I need to move my Solo 401k accounts or sell investments after changing from a sole proprietorship to an S corporation?

No. Changing from a sole proprietorship to an LLC taxed as an S corporation does not require moving Solo 401k accounts or selling investments. A custodian, such as a brokerage firm, may need notice of the new plan sponsor and a copy of the amendment so the funding account name matches its records.

Does changing to an S corporation change my Solo 401k contribution limits?

No. The 2026 Solo 401k limits stay the same after the entity change. They are a $24,500 employee deferral, an $8,000 catch-up, an $11,250 super catch-up for ages 60 to 63, and a $72,000 overall limit plus eligible catch-ups. The calculation changes, because S corporation contributions are based on W-2 wages instead of Schedule C income.

How are Solo 401k contributions calculated after a business becomes an S corporation?

After a business becomes an S corporation, Solo 401k contributions are calculated from W-2 wages rather than Schedule C net income. A sole proprietor starts from Schedule C line 31 net income less one-half of self-employment tax. When the change happens mid-year, each period is calculated separately, with one deferral limit and one combined base cap.

Do I need to update Form 5500-EZ after a business entity change?

Yes, if the Solo 401k plan has been filing Form 5500-EZ. The plan sponsor files the form when plan value exceeds $250,000. After an entity change, the form must list the new entity and its new business EIN, and the filer can link the prior name and EIN in the designated section.

This article is based on the live webinar hosted by My Solo 401k Financial.

Next step:

Ready to set up or update a plan? Open a Solo 401k account with My Solo 401k Financial. Plan documents are prepared within the same business day after the application is submitted and payment is made.

Educational purposes only: The material above is provided for educational purposes only. Nothing here should be construed as tax, legal, or investment advice, or as a solicitation. Consult a tax attorney and financial professional before making an investment decision.


Solo 401k Loan: Borrow Up to $50,000 to Pay Off 25% APR Card Debt

Solo 401k Loan: Borrow Up to $50,000 to Pay Off 25% APR Card Debt

A Solo 401k loan lets a self-employed owner borrow the lesser of 50% of the plan balance or $50,000 to pay off credit card debt. The owner repays the plan over five years. The interest, set at the prime rate plus 1%, is paid into the owner’s own Solo 401k account, not to a bank. The Solo 401k plan document must permit participant loans.

Solo 401k loan webinar: How to Pay Off Credit Card Debt With a Solo 401k Loan, a live session by My Solo 401k Financial, recorded .

Key Takeaways: Solo 401k Loan for Credit Card Debt

  • A Solo 401k loan is limited to the lesser of 50% of the account balance or $50,000.
  • A $30,000 credit card balance at 25% APR costs $7,500 a year in interest, or $625 a month, according to the webinar.
  • A Solo 401k loan used to pay off credit card debt must be amortized over 60 months with monthly or quarterly payments.
  • An unpaid Solo 401k loan balance becomes a deemed distribution, taxed as ordinary income plus a 10% penalty if the borrower is under age 59½.
  • Discount brokerage Solo 401k plans at Fidelity and Schwab do not allow loans, while plan documents from My Solo 401k Financial do, and loan documents are prepared within one business day.
  • The 12-month look-back rule reduces a new Solo 401k loan by the highest outstanding balance of any loan during the prior 12 months.

Can I use a Solo 401k loan to pay off credit card debt?

Yes. A Solo 401k loan can pay off credit card debt when the Solo 401k plan document permits participant loans, and the sections below cover the limits, rate, term, and risks.

How does a Solo 401k loan pay off credit card debt?

A Solo 401k loan replaces high-interest credit card debt with a loan from the borrower’s own retirement plan. The borrower takes cash from the plan, pays off the cards, and repays the plan with interest.

What does $30,000 of credit card debt at 25% APR cost each year?

Credit card debt of $30,000 at 25% APR costs $7,500 a year in interest. That works out to $625 every month. The interest payments themselves reduce no principal, and every dollar is a sunk cost paid to the bank.

“$30,000 at 25% APR. That would have an annual interest cost of $7,500. $625 every single month handed to the bank.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial
(2:00 in the webinar)

How does a Solo 401k loan let you become your own bank?

A Solo 401k loan works in three moves. The borrower first takes cash from the plan. The borrower then pays the credit cards down to zero, assuming the payoff amount is no more than the eligible loan amount. Finally, the borrower repays the plan in equal payments of principal and interest.

The interest rate on the Solo 401k loan is prime plus 1%, not the 25% card rate. That interest flows into the borrower’s own Solo 401k account.

“Here the interest is not 25%, instead it’s prime plus 1%, which currently as of the date of this webinar would be 8%. But that’s not going to a bank … It’s going into your own retirement account.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial
(4:47 in the webinar)

Who is eligible for a Solo 401k loan?

A Solo 401k loan requires a Solo 401k plan, and a Solo 401k plan requires self-employment. The solopreneur can have no full-time W-2 employees other than owners and their spouses. The plan document must also permit loans.

Credit card debt versus a Solo 401k loan on a $30,000 balance
Option Interest rate Who receives the interest Net wealth retained (per webinar)
Credit card debt ($30,000 at 25% APR) 25% APR The bank; $7,500 a year $0
Solo 401k loan ($30,000) Prime plus 1% (8% on the webinar date) [as of 9.24.2026] The borrower’s own Solo 401k account 100%, the interest plus the capital

Summary: On a $30,000 balance, credit card debt at 25% APR sends $7,500 a year in interest to a bank. A Solo 401k loan at prime plus 1% pays the interest into the borrower’s own Solo 401k account.

Example: A self-employed owner carries $30,000 of credit card debt at 25% APR. The owner takes a $30,000 Solo 401k loan, pays off the cards, and makes equal payments of principal and interest to the Solo 401k account. The bank no longer receives the $7,500 a year.

What are the Solo 401k loan limits and rules?

The Solo 401k loan is limited to 50% of the account balance, not to exceed $50,000.

“Number one, the loan is limited to 50% of your balance, not to exceed $50,000 … So you can look across your whole Solo 401k account value. So adding the pre-tax plus the Roth, for example, you take that amount 50% of it.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial
(5:32 in the webinar)

Can a Solo 401k loan come from Roth and pre-tax money?

A Solo 401k loan can come from the pre-tax account, the Roth account, or both. Borrowing from both requires two separate loans. Together, the two Solo 401k loans cannot exceed the lesser of 50% of the total balance or $50,000.

How long is the repayment term for a Solo 401k loan?

A Solo 401k loan used to pay off credit card debt has a five-year term. The loan must be amortized over 60 months, with monthly or quarterly payments. The payments must be made at least quarterly.

What interest rate applies to a Solo 401k loan?

The Solo 401k loan rate is prime plus 1%, or a CD rate plus 2%. The CD option uses a comparable CD. A $30,000 loan with a five-year term, for example, would use a $30,000 CD rate plus 2%.

The interest does not go to a bank, to My Solo 401k Financial, or to the plan provider. The interest goes into the borrower’s own Solo 401k account.

Which Solo 401k plans allow a loan?

A Solo 401k loan is available only when the underlying plan document allows participant loans. Plan documents at discount brokerages such as Fidelity and Schwab do not allow loans. A participant can still keep the account at Fidelity or Schwab.

Where Solo 401k plan documents come from and whether loans are allowed
Plan document source Solo 401k loan allowed Where the account can be held Loan documents
Discount brokerage plan documents (for example Fidelity or Schwab) No At that brokerage Not applicable
Plan documents from My Solo 401k Financial Yes At Fidelity, Schwab, or another bank or brokerage of choice Prepared within one business day at no additional charge for customers

Summary: Discount brokerage Solo 401k plan documents do not allow loans. Solo 401k plan documents from My Solo 401k Financial allow a Solo 401k loan and stay portable to Fidelity, Schwab, or another institution.

My Solo 401k Financial does not hold or have access to customer accounts. The plan is portable, so a customer obtains the plan documents and then opens an account at the institution of choice.

How do you take a Solo 401k loan in five steps?

Taking a Solo 401k loan follows five steps, as outlined in the webinar.

  1. Check your plan. The Solo 401k plan documents must allow a 401k participant loan.
  2. Verify the limits. The Solo 401k loan is limited to 50% of the balance, not to exceed $50,000.
  3. Set your rate. Use prime plus 1%, or a comparable CD rate plus 2%.
  4. Sign the note. My Solo 401k Financial prepares loan documents within one business day.
  5. Disburse the cash and pay off the card. Wipe out the credit card debt, then start repaying yourself instead of the bank.

My Solo 401k Financial prepares the required Solo 401k loan documents at no additional charge for customers. The customer submits a form on the website. The questionnaire asks how much to borrow and whether payments will be monthly or quarterly.

What are the risks of a Solo 401k loan?

Important: A defaulted Solo 401k loan is a taxable event. The unpaid balance is taxed as ordinary income, plus a 10% penalty if the borrower is under age 59½.

What happens if a Solo 401k loan goes into default?

A defaulted Solo 401k loan does not go on a credit report, unlike defaulted credit card debt. The consequence is tax instead. The unpaid balance is treated as a deemed distribution.

“Default does become a taxable event … the unpaid balance would trigger ordinary income tax plus a 10% penalty if you’re under age 59 and a half.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial
(9:43 in the webinar)

What is the investment opportunity cost of a Solo 401k loan?

A Solo 401k loan removes dollars from the plan that could otherwise be invested in stocks, bonds, or alternative investments. The borrower who repays the loan recoups the money plus interest. The Solo 401k account will still grow accordingly.

Does a Solo 401k loan require steady cash flow?

A Solo 401k loan requires steady cash flow. Repayments are due regardless of what happens in the business or on the borrower’s personal balance sheet, and regardless of what the borrower used the money for.

Which compliance mistakes make a Solo 401k loan costly?

A Solo 401k loan needs a written note. A loan with no documents is a compliance mistake, which is why My Solo 401k Financial prepares the loan documents for customers.

Missed repayments are the second mistake. A Solo 401k loan has a grace period for missed payments, after which the loan defaults.

“You have until the end of the quarter following the quarter when you miss the payment or payments to make up all the payments from the prior quarter. But if you’re not able to do that, then the loan will go into default.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial
(11:08 in the webinar)

Exceeding the caps is the third mistake. A Solo 401k loan cannot exceed 50% of the balance or $50,000, whichever is less.

How does the 12-month look-back rule affect a second Solo 401k loan?

The 12-month look-back rule applies when a borrower takes more than one Solo 401k loan. The borrower checks whether any Solo 401k loan was outstanding during the prior 12 months.

“You have to reduce how much you can take as that subsequent loan by the highest outstanding balance of any loan over the prior 12 months. Even if … at the time of the subsequent loan, you had already paid back that prior loan.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial
(12:39 in the webinar)

Can a Solo 401k loan be used for home improvement or other purposes?

A Solo 401k loan can be used for any purpose whatsoever, including home improvement. An attendee asked about home improvement live.

“Beyond credit cards, can we borrow for home improvement work? Yes, you can. You can really use the money for any purpose whatsoever.”

— Attendee question read aloud in the live webinar; answered by George Blower, Retirement Accounts Attorney, My Solo 401k Financial
(15:04 in the webinar)

A Solo 401k loan for home improvement still has a five-year term. Only a loan used to purchase a primary residence can extend beyond five years.

Solo 401k Loan FAQ

Can I use a Solo 401k loan to pay off credit card debt?

Yes. A Solo 401k loan can pay off credit card debt if the Solo 401k plan document permits participant loans. The borrower takes cash from the plan, zeroes out the cards, and repays the plan in equal payments of principal and interest, so the interest goes into the borrower’s own retirement account.

How much can I borrow with a Solo 401k loan?

A Solo 401k loan is limited to the lesser of 50% of the account balance or $50,000. The balance is measured across the whole Solo 401k account, adding pre-tax and Roth money together. A participant with a $100,000 balance can borrow up to $50,000, and a participant with $60,000 can borrow up to $30,000.

What interest rate does a Solo 401k loan charge?

The webinar described the Solo 401k loan rate as prime plus 1%, or a comparable CD rate plus 2%. The interest is not paid to a bank or to the plan provider. It is deposited into the borrower’s own Solo 401k account.

How long do I have to repay a Solo 401k loan used for credit cards?

A Solo 401k loan used to pay off credit card debt has a five-year term and must be amortized over 60 months. Payments can be monthly or quarterly, and the borrower chooses the schedule. Only a loan used to purchase a primary residence can extend beyond five years.

What happens if I default on a Solo 401k loan?

A defaulted Solo 401k loan does not appear on a credit report, but the unpaid balance becomes a taxable deemed distribution. The unpaid balance triggers ordinary income tax, plus a 10% penalty if the borrower is under age 59½. A missed payment can be cured until the end of the following quarter.

Can I take a Solo 401k loan from my Roth and pre-tax accounts?

Yes. A Solo 401k loan can come from the pre-tax account, the Roth account, or both. Borrowing from both accounts requires two separate loans. The combined amount of the two loans cannot exceed the lesser of 50% of the total balance or $50,000.

Does a Fidelity or Schwab Solo 401k allow loans?

No. The Solo 401k plan documents offered directly by discount brokerages such as Fidelity and Schwab do not allow loans. A participant can still hold the account at Fidelity or Schwab while using Solo 401k plan documents from My Solo 401k Financial, which do allow a Solo 401k loan.

Can I take a second Solo 401k loan after repaying the first?

Yes, but the 12-month look-back rule applies. A new Solo 401k loan must be reduced by the highest outstanding balance of any loan during the prior 12 months, even if that earlier loan is already repaid. The $50,000 and 50% caps still apply to the new loan.

This article is based on the live webinar hosted by My Solo 401k Financial.

Ready to open a Solo 401k plan that allows a Solo 401k loan?

Submit the application in about a minute. My Solo 401k Financial prepares the plan documents within the same business day once payment is made.

Open a Solo 401k account

Educational purposes only: This article is provided for educational purposes only. It should not be construed as tax, legal, or investment advice, and it is not a solicitation. Before making an investment decision, consult a tax attorney and a financial professional.


Solo 401(k) at Any Age: $72,000 Under 50, $83,250 at 60–63

Solo 401(k) at Any Age: $72,000 Under 50, $83,250 at 60–63

Direct Answer: A Solo 401(k) lets self-employed owners with no full-time non-owner, non-spouse employees contribute up to $72,000 for 2026. Owners age 50 to 59, or 64 and older, add an $8,000 catch-up, for up to $80,000. Owners age 60 through 63 add an $11,250 super catch-up instead, for up to $83,250. Each total requires enough self-employment income.

Key takeaways: Solo 401(k) limits for 2026

  • The overall Solo 401(k) contribution limit for 2026 is $72,000, combining employee, employer, and voluntary after-tax contributions, and it cannot exceed self-employment compensation.
  • The 2026 Solo 401(k) employee deferral limit is $24,500, capped at 100% of self-employment compensation.
  • Participants age 50 to 59, or 64 and older, at the end of 2026 may add an $8,000 catch-up contribution, raising the potential total to $80,000.
  • SECURE 2.0 created an $11,250 super catch-up for ages 60 to 63 in 2026, replacing the $8,000 catch-up and raising the potential total to $83,250.
  • A spouse who works in the business and has earned self-employment income can join the Solo 401(k), and two spouses could contribute $144,000 or more in 2026.
  • A Mega Backdoor Roth requires a plan document that allows voluntary after-tax contributions, and that standard discount-brokerage Solo 401(k) plans do not allow them.
  • Per IRS Publication 560 as cited in the webinar, the contribution deadline is the business tax return deadline, including timely filed extensions.

How much can I contribute to a Solo 401(k) in 2026 if I’m over 50?

A Solo 401(k) participant age 50 or older at the end of 2026 can add a catch-up contribution on top of the standard limits. The standard catch-up for 2026 is $8,000.

“So for 2026, your standard catch-up contribution amount is $8,000. Now, that’s on top of the $24,500 base because really the catch-up contribution is just an additional employee contribution.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial (6:39 in the webinar)

The Solo 401(k) catch-up rules for ages 50 to 59 also apply to anyone age 64 or older at the end of 2026. The $24,500 base deferral stays in place, and employer and voluntary after-tax contributions can still be added.

What is the Solo 401(k) super catch-up for ages 60 to 63?

SECURE 2.0 created a super catch-up contribution for Solo 401(k) participants age 60 to 63 as of the end of 2026. The super catch-up is $11,250 instead of the $8,000 standard catch-up.

“Now, with SECURE Act 2.0, an additional catch-up contribution bucket was created. Now, this is instead of your standard catch-up contribution. So instead of $8,000, if you’re age 60 to 63 as of the end of 2026, you can make a $11,250 super catch-up contribution.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial (8:41 in the webinar)

A Solo 401(k) participant in that age band can defer up to $35,750 as an employee. Adding employer or voluntary after-tax contributions brings potential 2026 contributions to $83,250, subject to income.

Solo 401(k) 2026 contribution limits by age group (as of December 31, 2026)
Age group Employee deferral Catch-up Total employee deferral Potential total with employer or after-tax
Under 50 $24,500 None $24,500 $72,000
50 to 59, or 64 and older $24,500 $8,000 $32,500 $80,000
60 to 63 $24,500 $11,250 (super catch-up) $35,750 $83,250

The Solo 401(k) 2026 potential total is $72,000 under age 50, $80,000 at ages 50 to 59 and 64 and older, and $83,250 at ages 60 to 63, each subject to sufficient self-employment income.

Example: A 61-year-old sole proprietor with enough income could defer $24,500 plus an $11,250 super catch-up, or $35,750, before any employer or after-tax contribution. The webinar puts the potential total for that age band at $83,250.

Live webinar: Never Too Late: Using a Solo 401(k) to Supercharge Your Retirement Savings at Any Age, hosted by My Solo 401k Financial.

Is it too late to open a Solo 401(k) for 2026?

A Solo 401(k) can still be established for 2026.

“There is good news though for solopreneurs who are therefore eligible to set up a Solo 401(k) as it is purpose-built to help you catch up fast. The clock is ticking, but the window is still open.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial (1:42 in the webinar)

My Solo 401k Financial establishes a Solo 401(k) within the same business day. This preserves the ability to make 2026 contributions by the 2026 business tax return deadline, including extensions into 2027.

“Now, for 2026, you have time. You can establish the plan by the end of the year. So, December 31st. And really, that just means signing up with My Solo 401k Financial because we established the plan within the same business day.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial (3:42 in the webinar)
Important: Solo 401(k) contribution deadlines depend on how the business is taxed. For example, April 15 or October 15 for a sole proprietorship and March 15 or September 15 for a calendar-year S corporation.

Who qualifies for a Solo 401(k)?

A Solo 401(k) is available to self-employed individuals with no full-time non-owner, non-spouse W-2 employees. A business owned by the individual or a spouse must have no such employees.

The Solo 401(k) has the highest contribution limits of any defined contribution plan available to self-employed individuals. The owner can contribute as both employee and employer, which fills multiple contribution buckets.

What are the Solo 401(k) contribution buckets?

A Solo 401(k) offers up to five buckets in 2026m. All contributions combined cannot exceed the lesser of self-employment compensation or the $72,000 overall limit, before catch-up.

Solo 401(k) contribution types and 2026 limits stated in the webinar
Contribution type Tax treatment 2026 limit stated in the webinar Who can use it
Employee deferral Pre-tax or Roth 100% of self-employment compensation, up to $24,500 All participants
Catch-up Employee contribution $8,000 Age 50 to 59, or 64 and older
Super catch-up Employee contribution $11,250 instead of $8,000 Age 60 to 63
Employer profit sharing Pre-tax 20% or 25% of self-employment income, depending on how the business is taxed All participants with self-employment income
Voluntary after-tax After-tax, convertible to Roth 100% of self-employment compensation, up to the $72,000 overall limit Plans that allow it

Can a spouse contribute to the same Solo 401(k)?

A spouse who works in the business can be added to the same Solo 401(k) and still keep it a Solo 401(k). The spouse receives a separate set of contribution buckets.

“So, if each spouse has the income to justify it between the two for 2026, they could be contributing $144,000 and more if they’re both eligible for catch-up contributions as well.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial (10:10 in the webinar)

The spouse does not need to own the business. The spouse must work in the business and have earned self-employment income. Each spouse’s limit depends on age, self-employment income, and contributions to any other plan.

What is a Mega Backdoor Roth in a Solo 401(k)?

A Mega Backdoor Roth saves more into a Roth account than standard Roth IRA or Roth 401(k) limits allow. A Solo 401(k) participant uses a two-step process.

Step one is a voluntary after-tax contribution, which the plan document must allow. Step two converts the after-tax funds to a Roth Solo 401(k) or a Roth IRA. Read the Mega Backdoor Roth Solo 401(k) guide for the full process.

“With the mega backdoor Roth individuals can contribute up to $72,000 for 2026 where those funds end up in your Roth account. So that’s almost 10 times what that individual could contribute for example to a Roth IRA.”

— George Blower, Retirement Accounts Attorney, My Solo 401k Financial (12:58 in the webinar)

The voluntary after-tax limit is 100% of self-employment compensation, dollar for dollar, up to the $72,000 overall limit. Other employee and employer contributions count toward that same overall limit.

Standard discount-brokerage Solo 401(k) plans do not allow Mega Backdoor Roth contributions. A participant needs a plan document that permits voluntary after-tax contributions.

How do traditional and Roth contributions compare in a Solo 401(k)?

A Solo 401(k) from My Solo 401k Financial allows traditional pre-tax, Roth, and Mega Backdoor Roth contributions. Traditional contributions reduce taxable income for the contribution year.

Roth contributions do not reduce taxable income for the contribution year, but they offer potential tax-free growth. Some commentators say traditional contributions suit a high bracket today, while Roth suits expected rate increases.

An in-plan Roth conversion moves pre-tax dollars already in the Solo 401(k) to Roth status. Tax is owed for the year of conversion, and later growth has the potential to be tax-free.

Can I roll an old 401(k) or IRA into a Solo 401(k)?

A Solo 401(k) can receive rollovers from a former employer plan or an IRA. Many participants age 50 and older consolidate old accounts into one Solo 401(k) for administrative ease.

A self-directed Solo 401(k) plan from My Solo 401k Financial allows stocks, bonds, mutual funds, real estate, private equity, precious metals, and cryptocurrency. Prohibited transaction rules still apply. A Solo 401(k) can invest in real estate but cannot rent it to the owner’s child.

Solo 401(k) FAQ: 2026 limits, catch-up, spouses, and Mega Backdoor Roth

What is the total Solo 401(k) contribution limit for 2026?

The total Solo 401(k) contribution limit for 2026 is $72,000, according to the webinar. The total combines employee, employer, and voluntary after-tax contributions and cannot exceed self-employment compensation. Participants age 50 or older can add an $8,000 catch-up, and those age 60 to 63 can add an $11,250 super catch-up instead, reaching $80,000 or $83,250 with enough income.

What is the Solo 401(k) super catch-up limit for ages 60 to 63?

The Solo 401(k) super catch-up limit for 2026 is $11,250 for participants age 60 to 63 as of the end of 2026. SECURE 2.0 created the super catch-up. The super catch-up replaces the standard $8,000 catch-up, so total employee deferrals can reach $35,750 and total potential contributions can reach $83,250 with enough self-employment income.

Can my spouse contribute to my Solo 401(k)?

A spouse can contribute to the same Solo 401(k) if the spouse works in the business and has earned self-employment income. The spouse does not need to own the business. Each spouse receives a separate set of contribution buckets. Two eligible spouses could contribute $144,000 or more in 2026, depending on age, income, and other plan contributions.

Can I still open a Solo 401(k) for 2026 in December?

A Solo 401(k) can be established for 2026 by December 31, 2026. My Solo 401k Financial establishes plans within the same business day. 2026 contributions can be made by the 2026 business tax return deadline, including extensions into 2027, and deadlines vary by business tax classification.

Can a Solo 401(k) after-tax contribution made in 2026 count for 2025?

Yes. IRS Publication 560 sets the contribution deadline at the business tax return deadline, including timely filed extensions. For example, a sole proprietorship can make 2025 contributions by April 15, or October 15 with an extension. A calendar-year S corporation can make them by March 15, or September 15 with an extension.

Does a Solo 401(k) allow Mega Backdoor Roth contributions?

A Solo 401(k) allows Mega Backdoor Roth contributions only if the plan document permits voluntary after-tax contributions. The process has two steps: make the after-tax contribution, then convert it to a Roth Solo 401(k) or Roth IRA. Standard discount-brokerage Solo 401(k) plans do not allow these contributions.

How is a Mega Backdoor Roth transfer reported on Form 1099-R?

A transfer to the Roth account is reported on Form 1099-R for the year of transfer, not the year of contribution. A 2025 contribution transferred in 2026 appears on the 2026 Form 1099-R. My Solo 401k Financial prepares the form at no additional charge as long as the client submits the website form in a timely manner.

This article is based on the live webinar hosted by My Solo 401k Financial.

Ready to start? My Solo 401k Financial prepares Solo 401(k) documents within the same business day. Open a Solo 401(k) account.
Educational purposes only: This article is provided for educational purposes only and is not tax, legal, or investment advice or a solicitation. Consult a tax attorney and financial professional before making an investment decision.


How does a ROBS 401(k) work?

How Does a ROBS 401(k) Work?

Direct Answer: A ROBS 401(k) — rollover business startup — lets an entrepreneur use retirement funds to buy stock in their own C corporation without triggering a taxable distribution. Funds move from an IRA or former employer plan into the ROBS 401(k), which then purchases private stock in the corporation. The owner must work as a W-2 employee at least 1,000 hours a year, and the ROBS 401(k) must file Form 5500 annually regardless of value.

How Does a ROBS 401(k) Work?

A ROBS 401(k) is short for “rollover as business startup.” It is a specialized retirement plan structure, not a loan, that allows an entrepreneur to invest eligible retirement funds directly into their own business as an equity purchase.

“It’s short for rollover as business startup… a specialized retirement plan structure that allows entrepreneurs to use eligible retirement funds to purchase a business or even fund an existing business.”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial (webinar recording )

Info: As of , the ROBS 401(k) structure is an existing, IRS-recognized retirement plan strategy — not proposed legislation. My Solo 401k Financial states it has offered the ROBS 401(k) for over 12 years.

Live Q&A webinar on how the ROBS 401(k) works, hosted by Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial.

Key Takeaways

  • A ROBS 401(k) requires forming a C corporation — not an S corporation or LLC — because only C corporations issue the stock the 401(k) must purchase to become a shareholder.
  • Taking a $100,000 distribution instead of using a ROBS 401(k) could leave an entrepreneur with as little as $60,000 after federal taxes, a 10% early-withdrawal penalty, and possible state taxes.
  • A ROBS 401(k) must file Form 5500 every year regardless of account value, unlike a Solo 401(k), which only files once assets exceed $250,000.
  • The ROBS 401(k) owner must work as a bona fide W-2 employee of the C corporation for at least 1,000 hours per year; a 1099 contractor arrangement does not qualify.
  • My Solo 401k Financial charges $3,000 for the first 12 months of ROBS 401(k) setup, then $899 annually starting in month 13 for ongoing compliance reporting.
  • A ROBS 401(k) cannot fund a business operated only by a family member, such as a son or spouse — the person contributing the retirement funds must also work as a W-2 employee of that business.
  • Once a W-2 employee works 1,000 hours in a year for the ROBS 401(k)-funded corporation, that employee must be offered a chance to participate in the 401(k) plan.

What Are the Steps to Set Up a ROBS 401(k)?

A ROBS 401(k) follows a specific sequence, and skipping or reordering a step can turn the transaction into a taxable distribution. First, a C corporation must be formed — the ROBS 401(k) cannot invest in an S corporation, because S corporation rules don’t allow a 401(k) or IRA to be a shareholder, and it cannot invest in an LLC, because LLCs issue membership units rather than stock.

“It has to be a C corporation. It cannot be an S corporation… It cannot be an LLC because an LLC issues units.”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial (webinar recording )

After the C corporation is formed, it adopts a qualified 401(k) plan — the ROBS 401(k) — which is signed via an adoption agreement. An existing IRA or former employer plan is then transferred directly into the ROBS 401(k) brokerage account, never into the corporation’s bank account. Finally, the ROBS 401(k) uses those funds to buy private stock in the C corporation, wiring funds directly from the ROBS 401(k) brokerage account to the corporation’s bank account.

Warning: If former employer plan or IRA funds are transferred to the corporation directly, bypassing the ROBS 401(k), that typically results in a taxable distribution instead of a tax-free investment.

Why Use a ROBS 401(k) Instead of Taking a Distribution?

A ROBS 401(k) avoids the tax bill that comes with cashing out a retirement account to fund a business. A pre-tax distribution triggers federal income tax and, if the account holder is under age 59½, a 10% early-withdrawal penalty, plus state taxes depending on residency.

“If you took a $100,000 distribution from your IRA or former employer plan, you may end up only… receiving $60,000 because of all the taxes and penalties.”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial (webinar recording )
Example: Because ROBS 401(k) funds move directly from a former employer plan or IRA into the ROBS 401(k) brokerage account, then into the C corporation, the funds never pass through the owner’s personal bank account — which is exactly why the transaction is not treated as a taxable distribution.

A ROBS 401(k) Is Not a Participant Loan

A ROBS 401(k) is an equity investment, not a loan, and nothing needs to be repaid to the plan.

“A ROBS is not a participant loan… The corporation is not allowed to borrow funds from your ROBS 401(k). That’s not the way the ROBS 401(k) works.”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial (webinar recording)

ROBS 401(k) vs. Solo 401(k): Key Differences

Comparing a ROBS 401(k) with a Solo 401(k) on business investment, Form 5500 filing, and participant loans.
Plan Type Can Invest in Your Own Business? Form 5500 Filing Requirement Participant Loan Available?
ROBS 401(k) Yes — via stock purchase in a C corporation Required every year, regardless of value No — it’s an equity investment, not a loan
Solo 401(k) No Required only once plan assets exceed $250,000 (Form 5500-EZ) Yes — up to 50% of balance, capped at $50,000

In short: a ROBS 401(k) always files Form 5500, while a Solo 401(k) only files once it crosses the $250,000 threshold — and only the ROBS 401(k) can legally purchase stock in the owner’s own business.

“Owners sometimes assume the under $250,000 filing exemption available to one-participant solo plans… applies to the ROBS. The IRS has explained that the one-participant exception does not apply.”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial (webinar recording )

Can a ROBS 401(k) Fund a Family Member’s Business?

No. A ROBS 401(k) can only finance a business in which the person contributing the retirement funds also works as a W-2 employee. A parent cannot use their own ROBS 401(k) to fund a business their adult child will run alone.

“Unfortunately, the 401(k) regulations do not allow you to use your ROBS 401(k) to finance your son’s business or your wife’s business, for that matter.”

— Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial (webinar recording )
Example: A parent’s ROBS 401(k) could help fund a business as long as the parent also works there as a W-2 employee for at least 1,000 hours per year — their child could work there too, but only alongside the parent’s own qualifying employment, not in place of it.

What Are the Ongoing ROBS 401(k) Compliance Requirements?

A ROBS 401(k) is an ongoing qualified plan, not a one-time funding event, and carries compliance obligations at both the corporate and plan level. The C corporation must file its own corporate tax return (Form 1120), and its stock must be valued annually once the business has been operating — a new business being funded for the first time has no valuation requirement.

Hiring W-2 Employees Triggers Plan Eligibility

Once a W-2 employee works 1,000 hours or more in a 12-month period for the ROBS 401(k)-funded corporation, that employee must be offered the chance to participate in the 401(k), including the ability to buy stock in the corporation. An employee can decline in writing with a revocable waiver, but the offer must be made.

Important: The IRS has identified ROBS 401(k) arrangements where plan provisions were changed after the initial stock purchase specifically to prevent other participants from accessing the same stock feature, warning that these arrangements can create coverage, non-discrimination, and benefit rights problems.

What Counts as a Prohibited Transaction in a ROBS 401(k)?

A ROBS 401(k) remains subject to the same prohibited transaction rules as any qualified retirement plan. Using ROBS 401(k) or ROBS-funded corporation assets for personal benefit — beyond a reasonable W-2 salary — is prohibited, as is lending funds from the corporation or the plan to a disqualified person, or selling property between the corporation and a disqualified person.

Example: If a ROBS 401(k)-funded corporation owns a warehouse, the owner’s family member cannot use that warehouse to store equipment for a personal side business — furnishing facilities or services between the corporation and a disqualified person is prohibited.

What Happens When a ROBS 401(k)-Funded Business Is Sold?

Proceeds from selling a ROBS 401(k)-funded business return to the corporation’s bank account first, then flow back to the ROBS 401(k) brokerage account, since the ROBS 401(k) is the shareholder being bought out. Those funds can then be transferred to an IRA, and a final Form 5500 is filed to close the plan.

How Long Does a ROBS 401(k) Take and How Much Does It Cost?

A ROBS 401(k) can be completed in as little as 10 to 15 business days, though delays with a former employer plan’s transfer processing can extend the timeline to roughly 30 business days. My Solo 401k Financial charges $3,000 for the first 12 months of ROBS 401(k) setup, covering corporation and 401(k) formation, followed by an $899 annual fee starting in month 13 that covers ongoing compliance reporting.

Live Webinar Questions About ROBS 401(k) Plans

Is There a Similar Webinar for Solo 401(k) Backdoor Roth Conversions?

An attendee asked whether a comparable session covers the Solo 401(k) and Mega Backdoor Roth strategy.

“Is there a similar webinar for solo 401k that sets up after tax 401k with backdoor Roth conversion?”

— Webinar attendee, live Q&A (webinar recording )

Mark Nolan confirmed that the Mega Backdoor Roth Solo 401(k) strategy is a separate topic covered in other webinars, and that My Solo 401k Financial has offered it since 2013.

Will There Be Initial and Ongoing Costs?

A second attendee asked about ROBS 401(k) pricing.

“Will you be discussing initial costs and any ongoing costs, if any?”

— Webinar attendee, live Q&A (webinar recording )

Mark Nolan pointed to the firm’s pricing page and confirmed the $3,000 first-year setup fee and $899 annual fee described above.

Note: One additional live exchange referenced a spouse co-owning a business with the attendee, but the attendee’s original chat message was not clearly captured in the recording audio [VERIFY: attendee question wording not captured in recording]. Mark Nolan’s response confirmed that spouses working for the same self-employed business can each process their own Mega Backdoor Roth Solo 401(k) conversion.

Glossary

ROBS 401(k)
“Rollover as business startup” — a retirement plan structure that lets an entrepreneur use IRA or former employer plan funds to buy stock in their own C corporation without a taxable distribution.
C Corporation
The only entity type a ROBS 401(k) can invest in, because C corporations issue stock; S corporations and LLCs are not eligible.
Equity Investment (vs. Loan)
The ROBS 401(k) purchases private stock in the corporation and becomes a shareholder; nothing is borrowed and nothing must be repaid, unlike a 401(k) participant loan.
Form 5500
The annual informational return a ROBS 401(k) must file every year regardless of plan value, because the plan owns the business through its stock rather than the individual owning it personally.
1,000-Hour W-2 Rule
The requirement that the ROBS 401(k) owner work as a bona fide W-2 employee of the funded C corporation for at least 1,000 hours per year to satisfy IRS rules.

Frequently Asked Questions

How does a ROBS 401(k) work?

A ROBS 401(k) rolls IRA or former employer plan funds directly into a new 401(k), which then purchases private stock in a newly formed C corporation. The owner must work as a W-2 employee of that corporation for at least 1,000 hours a year, and the transaction is treated as an equity investment rather than a taxable distribution.

Can a ROBS 401(k) be used with an S corporation or LLC?

No. A ROBS 401(k) can only invest in a C corporation, because C corporations issue stock. S corporations cannot have a 401(k) or IRA as a shareholder, and LLCs issue membership units rather than stock, so neither qualifies for the ROBS 401(k) structure.

Is a ROBS 401(k) considered a loan?

No. A ROBS 401(k) is an equity investment, not a participant loan. The plan buys shares of stock in the C corporation and becomes a shareholder; there is no repayment schedule, unlike a 401(k) participant loan, which must be paid back.

Can I use my ROBS 401(k) to fund my son’s or spouse’s business?

No, not by itself. A ROBS 401(k) can only fund a business in which the person contributing the retirement funds also works as a W-2 employee for at least 1,000 hours per year. A family member can also work at the business, but cannot be the only one working there.

Does a ROBS 401(k) have to file Form 5500 every year?

Yes, every year, regardless of the plan’s dollar value. This differs from a Solo 401(k), which only files Form 5500-EZ once assets exceed $250,000, because the IRS treats the ROBS 401(k) as owning the business through its stock rather than the individual owning it personally.

Is there a similar webinar for Solo 401(k) backdoor Roth conversions?

Yes. My Solo 401k Financial covers the Mega Backdoor Roth Solo 401(k) strategy in separate sessions and states it has offered this strategy since 2013, processing thousands of conversions for owner-only and husband-and-wife businesses.

How much does a ROBS 401(k) cost?

My Solo 401k Financial charges $3,000 for the first 12 months, covering C corporation and 401(k) formation, followed by an $899 annual fee starting in month 13 that covers ongoing ROBS 401(k) compliance reporting, including the annual Form 5500 filing.

What counts as a prohibited transaction in a ROBS 401(k)?

Examples include using ROBS 401(k) or corporation assets for personal benefit beyond a reasonable W-2 salary, lending plan or corporate funds to a disqualified person, selling property between the corporation and a disqualified person, and letting a disqualified person use corporation-owned assets, such as a warehouse, for personal purposes.

This article is based on the [VERIFY: webinar date] live webinar hosted by My Solo 401k Financial. Analysis by Mark Nolan, Founder/ Compliance Officer, My Solo 401k Financial.

Ready to explore a ROBS 401(k) for your business?
Learn more about setting up a plan with My Solo 401k Financial →
Educational purposes only: This article summarizes general information from a live webinar and does not constitute individualized tax, legal, or financial advice. Consult a CPA or financial advisor before investing retirement funds in your own business through a ROBS 401(k).
  •  

  • About MySolo401k

    We help our clients take control of their retirement money. Our products and services provide our clients the freedom to invest their retirement savings in their own business as well as alternative investments such as real estate, private companies, promissory notes, precious metals, tax liens and equities.
    Learn more

    Connect with us

  • We’re here to help.

    Call: 800-489-7571

    Monday-Friday

    8:00 am - 4:00 pm PT

    Why us?
MENU