


As retirement savings rules evolve, solo 401k owners have even greater opportunities to accelerate tax‑advantaged retirement savings — especially if they’re nearing retirement age. For the 2026 tax year, the IRS updated contribution limits and introduced enhanced catch‑up and super catch‑up provisions under the SECURE 2.0 Act of 2022. Here’s a clear breakdown of what these are, how they differ, and how they apply to Solo 401k plans.
Solo 401k Contribution Basics for 2026

Before diving into catch‑up contributions, it helps to know the baseline Solo 401k limits:
-
Standard elective deferral limit: $24,500 for 2026
-
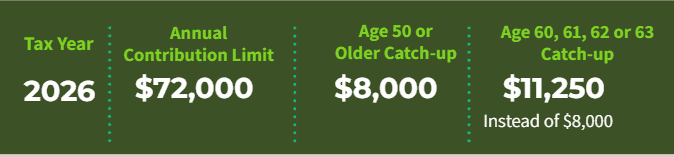
Combined limit: The total of employee (elective) plus employer (profit‑sharing), and voluntary after-tax contributions is governed by the annual additions limit (typically $72,000).
These base limits apply to all solo 401k participants, regardless of age. However, Catch‑up and super catch‑up contributions for older solo 401k participants allows for greater contribution amounts.
What Are Catch‑Up Contributions?
Catch‑up contributions are additional elective deferrals allowed for participants who are age 50 or older by the end of the tax year — a way to “catch up” on retirement savings if earlier contributions were lower.
For 2026:
-
Participants 50 and older can contribute an extra $8,000 on top of the base $24,500 elective deferral limit.
-
This means someone age 50+ can defer up to $32,500 as elective contributions in 2026 (not including employer profit‑sharing and voluntary after tax).
-
What Are Super Catch‑Up Contributions?
Super catch‑up contributions were first available in 2025 stemming from the passage of the SECURE 2.0 Act and continue in 2026. Solo 401k participants who are ages 60 through 63 by the end of the calendar year, so December 31, 2026, will be eligible to to make catch-up contributions up to $11,250. While These amounts will be adjusted for cost-of-living increases in future years, the super catch-up contribution remained the same as in 2025.
For 2026:
-
Solo 401k Participants in this age range can contribute up to $11,250 in catch‑up contributions instead of $8,000. That gives a total possible elective deferral of $35,750 before employer contributions or voluntary after-tax solo 401k contributions.
Key Differences: Catch‑Up vs. Super Catch‑Up
| Feature | Catch‑Up (Age 50+) | Super Catch‑Up (Age 60‑63) |
|---|---|---|
| Eligibility | Age 50 or older | Age 60‑63 |
| Extra Contribution Allowed (2026) | $8,000 | $11,250 |
| Type of Contribution | Elective deferral | Elective deferral |
| Relationship to Age | Begins at age 50 | Enhanced only ages 60‑63 |
| Applies In | All plans that allow catch‑ups | All plans that allow catch‑ups |
Summary: Standard catch‑up gives older solo 401k participants an additional $8,000 beyond the base limit. Super catch‑up boosts that additional portion to $11,250 for those closer to retirement.
Roth Requirement for High Earners (2026 Rule)
Beginning January 1, 2026, the SECURE Act 2.0 requires that catch-up contributions for higher-paid employees be made on a Roth (after-tax) basis.
Who Is Affected
The mandatory Roth catch-up rule applies to participants in:
-
401(k) plans (including Solo 401k plans)
-
403(b) plans
-
Governmental 457(b) plans
The rule applies to both:
-
Regular catch-up contributions — for participants age 50 or older, and
-
“Super catch-up” contributions — for participants who turn 60, 61, 62, or 63 in the year (a new feature under SECURE 2.0).
Under the new regulation, catch-up contributions must be Roth if the participant is a “high-paid employee.”
Key Takeaways for Solo 401k Owners
For Solo 401k participants:
-
If you’re self-employed with no W-2 wages, you’re exempt from the mandatory Roth catch-up rule.
-
If your Solo 401k is sponsored by an S-Corp or C-Corp and your W-2 income exceeds $150,000 (indexed) in 2025, your catch-up contributions for 2026 must be Roth. Visit here to learn more.
Conclusion
For the 2026 tax year, Solo 401k catch‑up contributions allow participants age 50+ to defer an additional $8,000 beyond the base limit, while those 60‑63 can make an extra $11,250 through super catch‑ups — all before counting employer contributions. High‑earning participants must also consider that catch‑up and super catch‑up contributions may need to be Roth contributions under the new SECURE 2.0 requirements.
Understanding these distinctions helps solo business owners make the most of their retirement savings opportunities as they approach retirement age.




