


When seeking to open Solo 401k, first familiarize yourself with the controlled group definition as it may restrict you from opening a Solo 401k. When a business is treated as a member of a controlled group, the controlled group is treated by the IRS as a single employer for retirement plan purposes, including Solo 401k plan; all the businesses are treated as one business. As such, the employer must take into account all employees of the controlled group of businesses when determining employee eligibility and making contributions to a SEP, SIMPLE or qualified retirement plan, including a Solo 401k.
Controlled Group Defined
Two or more trades or businesses under common control–related through common ownership interests–make up a controlled group (Treasury Regulation 1.414(c)-2). A controlled group of employers may take any form such as sole proprietorships, partnerships, S-Corporations and C-Corporations, LLC and tax-exempt organizations, or a combination of any of these.
Controlled Groups Types
If the business owner has multiple businesses and is looking to open Solo 401k, he or she should first consult with his or her tax advisor to ascertain if multiple businesses make up a controlled group. There are three different types of controlled groups.
Type 1: Parent-Subsidiary Controlled Group
A parent-subsidiary controlled group is made up of a parent organization and one or more subsidiary organizations or affiliates of the parent organization. To make up a parent-subsidiary group, the parent organization must own at least 80 percent of one or more subsidiary organization (commonly known as having a “controlling interest”). Furthermore, at least 80 percent of each subsidiary organization must be owned by other members (if any) of the parent-subsidiary controlled group.
Type 2: Brother-Sister Controlled Group
To be considered a brother-sister controlled group, the same five or fewer persons must own, in aggregate, at least 80 percent of each of the organizations in the brother-sister controlled group. Also, the same five or fewer persons who meet the controlling interest requirement must have effective control (ownership of more than 50 percent) of each organization.
Type 3: Combined Controlled Group
A combined controlled group is made up of both parent subsidiary and brother-sister controlled groups that have a common parent organization from the parent subsidiary that is also a member of the brother-sister controlled group.
Determining Ownership
As you have noticed, each of these types of controlled groups focus on ownership. What formulates ownership for purpose of a controlled group varies depending on the types of entity being considered (e.g., corporations, partnerships, sole proprietorships, trusts, estates). To determine if a business is a member of a controlled group, the employer–often with the assistance of his or her personal accountant–must first determine ownership by answering two basic questions:
1. Which individuals or entities have ownership interest in the business?
2. What, if any, ownership interest does the business have in other businesses?
Summary
A controlled group of employers is treated as one employer for Solo 401k eligibility purpose. This means that all employees under that group must be considered for eligibility for the plan. If eligible to participate, all employees (including the owner) must receive plan contributions and therefore a traditional 401k instead of a Solo 401k plan must be opened.
Attribution Rules QUESTION:
While I know I'm currently eligible to establish a Solo 401k, I'm trying to determine if I will be able to continuing using in a few years given the situation described below. Does the IRS approve the following situation? I open a Solo 401k plan for my single-member LLC. My wife has no ownership of my LLC and does not make contributions to the Solo 401k plan. Separately, she also has her own LLC that is currently a single-member LLC. In 2-3 years, she plans to open a law practice and expects to hire full-time W-2 employees. Because she has no ownership in my LLC, did not contribute to the Solo 401k plan and I have no ownership in her LLC (that now has employees), I plan to continue contributing and operating the Solo 401k since I still don't have any employees in my LLC. Does the IRS allow this or would the Solo 401k be disqualified simply because of our marriage even though we've kept our two businesses separate?
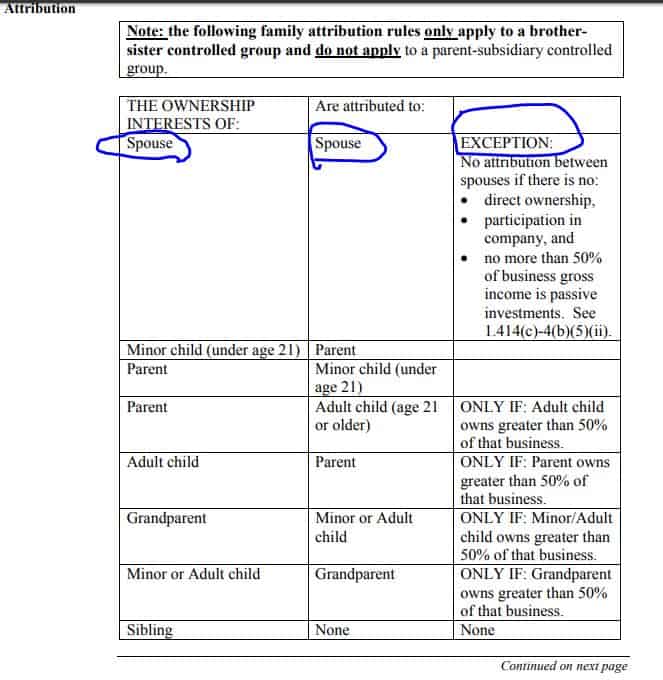
Typically, your spouse’s ownership of the LLC would be attributed to you such that if the other LLC had employees it would prevent you from opening a solo 401(k). In order to avoid the application of these attribution rules (And assuming that there is no interaction whatsoever such that the affiliated service group rules would not apply), you would not be permitted to have any direct ownership nor even participate in her business. See the discussion of the attribution rules as they applied to controlled groups at the following:
https://www.irs.gov/pub/irs-tege/epchd704.pdf
Wife’s Business QUESTION:
I have been told by my attorney/accountant that I am no longer eligible for a solo 401k and should convert to a safe harbor plan. The current plan is under my LLC, which is a single member LLC with no employees owned entirely by me. But my wife is the sole member of another LLC that does have a full-time employee. I am being told that since we are married the employee would basically be considered mine as well.
2 Separate Businesses QUESTION:
Business #1 (has W-2 employees) husband owns 50% wife owns 50% Business #2 (no employees) wife own 100% Can wife open a solo 401k plan?
Assuming business 1 and 2 don't do business with each other, and the wife will no longer own 50% of business 1, business 2 can sponsor a solo 401k plan but only the wife can participate (not the husband).
Existing Businesses QUESTIONS:
Currently one of my self-employed businesses sponsors a solo 401k which is a S-Corp and I own 100%. My wife is an employee and so the 2 of us are the Solo 401K plan participants. I want to know how much ownership I can have in other/separate businesses (LLCs or S-Corp) without violating any of the rules. I would think I can have any size ownership as long as there are no employees in any of those other businesses, but what if I own a percentage of one of those entities and there are employees?
Your understanding is correct, as long as the new company does not have any full-time W2 employee. You ownership percentage would not affect your eligibility. However, the income from all your self employment activity would need to be aggregated from a contribution perspective (meaning: if one company reported a gain and the other had losses you would need to net them together).
Can I own 100% if there are any number of employees as long as no employee works more that 1000 hours in a year?
Correct, if you do have employees then each employee needs to work less than 1,000 hours a year.
Or do I need to own only 50% or less if there are employees working for one of those entities as long as there are no employees working over 1000 hours per year?
In order for your self-employed business and the other entity/entities form a controlled group: you, your spouse or another related party such as your mother, father, son or daughter would need to have a combined ownership percentage of less than 80% of the other entity. Therefore, even if the company had full-time W2 employees, the controlled group rules would not impact your Solo 401k as long as you together with related persons do not own 80% or more of such company. Please note that even if there is no impact under the controlled group rules, per the affiliated service group rules if you (or a related person) own less than 80% of a company with full-time w-2 employees & that company is affiliated with your self-employed business which sponsors the Solo 401k (e.g. interacting directly or indirectly, serving the same customers, etc.) the two businesses may constitute an affiliated service group (even though you own less than 80% of the other business with employees) which means that the employees of the other business will be considered employees for purposes of the Solo 401k and you will no longer be able to maintain the Solo 401k.
S-Corporation with Family Members QUESTION:
My husband and I are 61% owners on an S corp with some other family members. We have full-time employees and would like to set up a solo 401k. I understand that the solo is for people who do not have full-time employees. We do however have a property management business that runs airbnb's my husband and I are the LLC owner-operators of this. I'm thinking if we opened up our solo 401 through this business we would not have much to fund the 401K. Is it possible to take wages earned from the S Corp and put them into the 401K that we opened under the property management company? Thanks for your time and assistance.
You could only open a Solo 401k under the latter entity (LLC) if the ownership in the S-corp with employees held by you and your spouse along with any interest held by your parents and/or kids (if any) was less then 80% and the S-corp had nothing to do with the LLC (and further provided that you don't have any other business with employees). Even if you could open a Solo 401k under the LLC, you would not be able to make contributions based on wages earned in the S-corporation.
Change in Self-Employed Business QUESTION:
This is acceptable assuming the new business does not have any non-owner employees. If you close the existing plan sponsor business and change it to your new business, then you will need to let us know so we can amend the plan to change the plan sponsor business. I have a question regarding my solo 401k account. I have registered another business with same partners as the business I have as "adopting employer" for current plan. Right now I am planning to have businesses active. At some point, I might want to close down the business that is "adopting employer". What are my options to use same plan for both now and just the new one at some point? The new business will not be generating any money for this year and probably next year too so I am not in a rush.
Interaction QUESTION:
What is the definition of direct interaction between companies?
The terms are not specifically defined in the regulations or guidance and trying to come up with a proper definition would take too much time (compare: I understand that the person who wrote the first Oxford dictionary is referred to as a "madman"). It's best to take a broad approach and analyze each scenario based on the facts and circumstance.
Affiliated Service Group QUESTION:
What is the layman’s term definition of affiliated service group?
It is worth noting first of all affiliated service group rules were put in place in response to the market trying to circumvent the controlled group rules. An example of an affiliated service group would be two companies that although they don't share common ownership (and therefore don't constitute a controlled group) still work together to serve the same customers (e.g. a management company that provides management services to another company)
2 (Two) Solo 401k Plans QUESTION:
I have a multi member LLC (me and a friend owned 50/50), taxed as a partnership. I also do 1099 contract work on the side (not related to the LLC or through the LLC). Do I use the same solo 401k I am opening through you for my 1099 income for both the multi member LLC income and the 1099 contract work income (not related to the LLC) or do I need to have one solo 401k for each income source, my 1099 income and the income from the multi member LLC?
Good question. You would need to open a second solo 401k that would be sponsored by the muti member LLC since it has another owner.
You can only contribute to this solo 401k ( Veritas Retirement Trust) based on net self-employment income generated through the sole proprietorship not the multi member LLC since that LLC has another parner.
However, if you end up opening multiple solo 401k plans, you will be able to double up on contributions since you are not sole owner of the multi member LLC and that LLC is not associated with hour sole prop businesses (i.e.,g they don't do business with each other and they are not affiliated). https://www.mysolo401k.net/what-is-the-laymans-term-definition-of-affiliated-service-group-for-solo-401k-eligibility-purposes/
Not Your Typical Solo 401k Control Group QUESTION:
I would like to know if I am eligible for solo 401K. Since my husband and I are owning 3 companies now, it seems to be a little complicated. Company 1: 100% Husband owned. All part-time employees Company 2: 100% Wife owned. All part-time employees Company 3: 50% Husband owned, 50% Wife owned. No employees I believe we can open solo 401K as long as we don't have part-time employees. However, one of our employees is working part-time in both Company 1 and 2, so she is working more than 1000 hours if we combine her working hours in both Company 1 and 2. I would like to know if we are still eligible for solo 401K?
Unfortunately, neither your nor your spouse would qualify for a solo 401k plan because the W-2 employee works over 1,000 hours when her hours are aggregated for both businesses. Essentially, by the W-2 employee working for both businesses, the affiliated service group rules come into play as outlined on page 38 of the IRS Chapter 7 found HERE.


