
Once the solo 401k has been funded, there is no waiting period for processing a solo 401k participant loan.
You, as trustee/participant can take a loan/borrow from Solo 401k for any reason.
Following are some quick facts regarding the solo 401k participant loan rules.
- Each participant can borrow from the solo 401k provided each has a solo 401k balance; however, the solo 401k loan calculation is based on each solo 41k participant’s respective loan balance–not the entire value of the solo 401k plan.
- The solo 401k loan does not affect your personal credit or business credit score because you are borrowing from the solo 401k plan; therefore, there is no credit check.
- The Solo 401k loan term is 5 years for general loans.
- The Solo 401k loan term can be more than 5 years not to exceed 15 years if used to purchase principal residence for you as trustee/participant of the Solo 401k.
- Solo 401k loan payments are made either monthly or quarterly.
- Solo 401k annual contributions from self-employment income cannot be used/applied towards payment of solo 401k participant loans.
- Solo 401k participant loan payments must be made with personal funds, not business funds or solo 401k funds.
- Since the solo 401k participant is borrowing from the solo 401k plan, at time of loan the loan proceeds must flow to the solo 401k participant’s bank account, not her business. Once the funds are in your personal bank account, you can then disburse them however you wish including placing them in your own business bank account.
- The interest rate for Solo 401k loan is either: A certificate deposit rate plus 2 percent or the prime rate plus 1 percent.
- Solo 401k Loan payments are fixed payments consisting of interest and principal
- Solo 401k loan rules do not allow for Interest only payments or principal payments only.
- Each solo 401k participant can borrow from his or her respective solo 401k balance. For example, if both spouse’s are participating in the solo 401k plan and have account balances, each can borrow up to the statutory limits described below.
- The maximum Solo 401k loan amount is either 50% of account balance or maximum amount of $50K.
– Example 1: Solo 401k balance is $50K; 50% of $50K = $25K (the Solo 401k maximum loan amount)
– Example 2: Solo 401k balance is $150K; 50% of $150K = $75K; however, the maximum permitted Solo 401k loan amount is $50K
– The minimum Solo 401k loan amount is $1,000.
- The Solo 401k rules require the following proper Solo 401k loan documentation:
– Solo 401k Loan Agreement
– Solo 401k Loan Application
– Solo 401k Loan Payment Amortization Schedule
You can obtain more information regarding borrowing/taking a participant loan from a Solo 401k at: https://www.mysolo401k.net/Solo401kLoan.html
Primary Residence Rule QUESTION:
I have a question about the primary residence rules for loans. I'd like to pay down the balance on my primary residence because it would remove the PMI on the loan. Would this satisfy the IRS regulations about the 401k loan for primary residence so I can qualify for a longer repayment period?
You can only borrow from your solo 401k for 5 years not 15 years because the 15 year rule applies to the purchase of a primary residence not the payoff of a primary residence.
Invest Loan Funds in Own Business QUESTION:
I own a small business where currently I am the sole employee. Is it possible for me to use some of my retirement funds to invest in that business, say for marketing purposes, to help me get it off the ground?
You could take a solo 401k participant loan and then use those funds for any purpose including investing in your own business. See the following. https://www.mysolo401k.net/solo-401k-participant-loan-facts-borrowing-solo-401k-2/
- Client Success Stories:
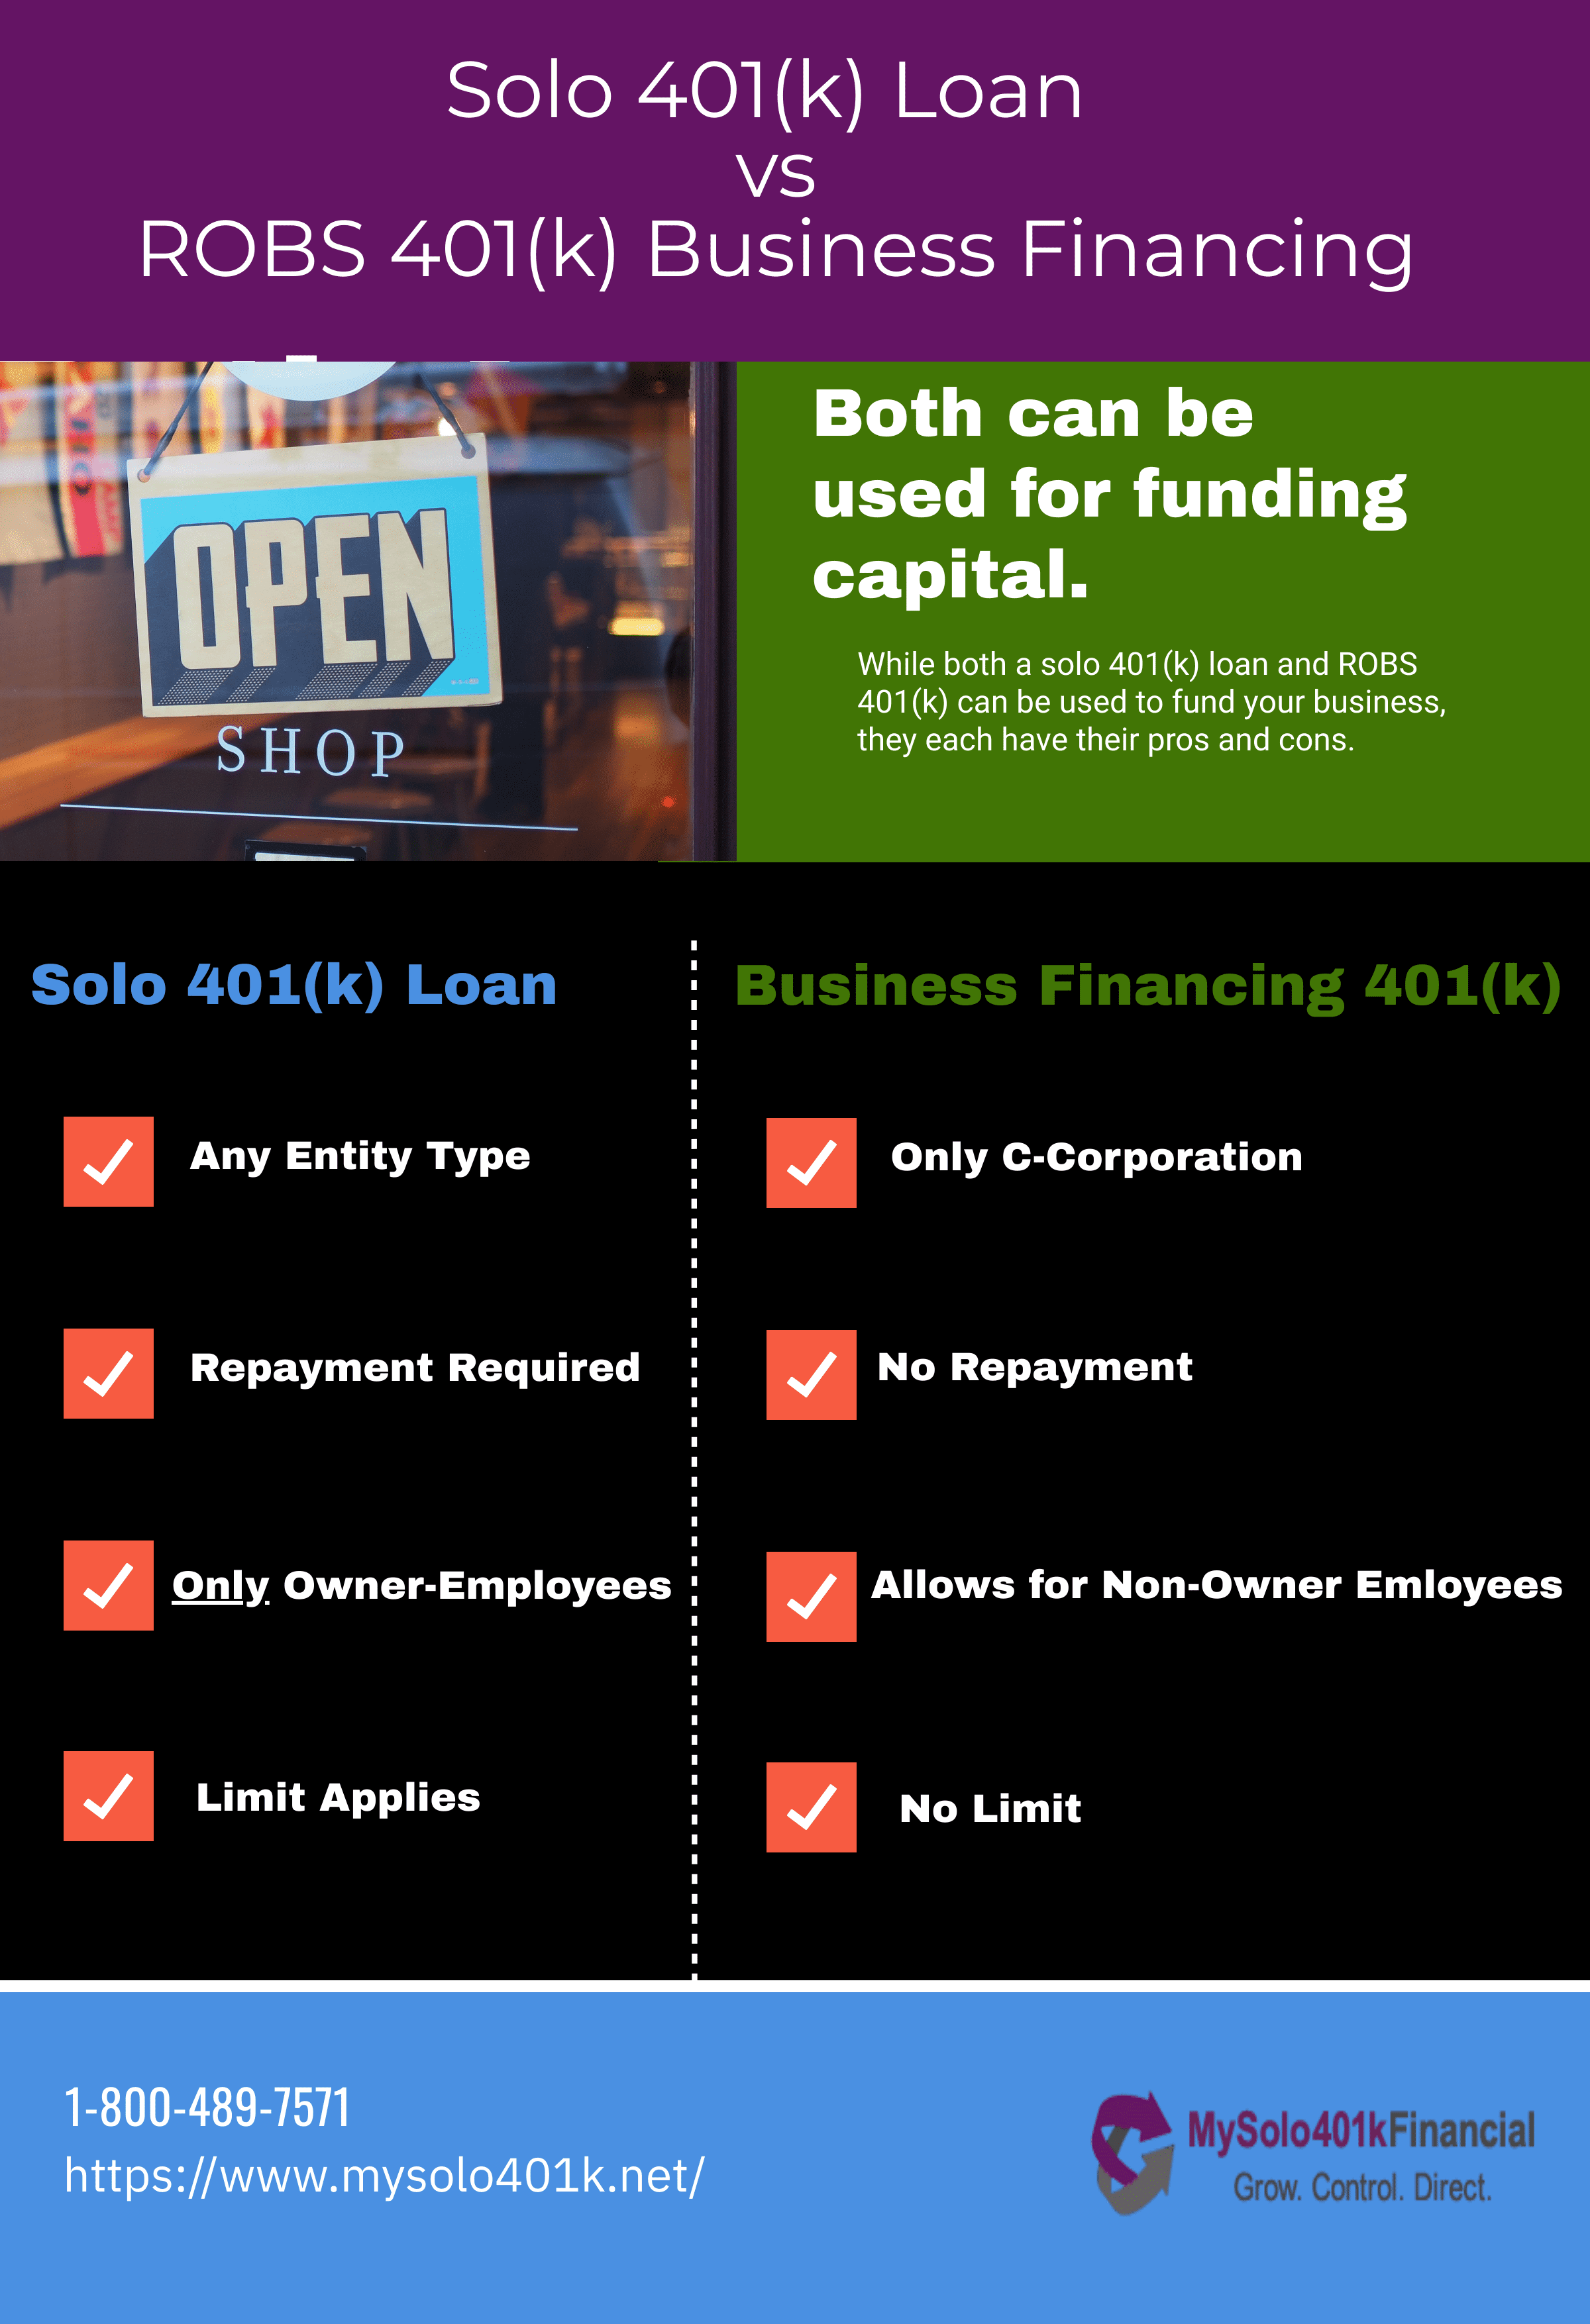
Another option besides the solo 401k plan is our ROBS 401k plan (business financing 401k plan). The ROBS 401k allows for investing in stock of your own C-corporation so it is not considered a loan but rather and equity investment. To learn more about the ROBS 401k plan, see the following:
https://www.mysolo401k.net/401k-business-financing/business-financing-401k-robs/
Loan to My Own Business QUESTION:
Can I give my company a loan through my solo401k and pay back principle plus interest?
A solo 401k participant loan to your own business is prohibited, but a solo 401k participant loan to you is allowed and you can do whatever you'd like with the loan proceeds including investing them in your own business.
Making Loan Payments Direct Deposit QUESTION:
Is it okay if I repay the solo 401k participant loan with direct ACH transfers between my personal bank account and the solo 401k Trust's bank account?
Yes that way you can place your solo 401k participant loan payments on autopilot, as the loan payments can be made by check or electronically. Depending on where you opened your solo 401k bank account, you will need to work with that financial institution to setup the ACH payments. For example, many of our clients use Fidelity Investments for their solo 401k bank account which allows for ACH transfers. See the following:
Fidelity ACH Instructions:
https://www.fidelity.com/cash-management/deposit-money/determine-routing-and-account-number
Early Payoff QUESTION:
If I pay off the solo 401k participant loan early, is there a penalty?
Is interest rate prorated QUESTION:
If I pay the solo 401k participant loan early, will the interest be prorated daily?
Yes, the interest on the solo 401k participant loan will be prorated in the sense that you will not pay the full amount of interest as you would otherwise pay if you paid the loan over the full term. Here is a helpful link regarding paying off a participant loan early: https://www.mysolo401k.net/pay-off-early-solo-401k-participant-loan/.
Loan Frequency QUESTION:
How frequently can you take a solo 401k participant loan?
You can borrow every 12 months but the 50% of account value not to exceed $50,00 applies in aggregate. See the following for more on this rule. https://www.mysolo401k.net/solo-401k-loan-limits/
Pay Taxes On Loan Payments QUESTION:
When i repay a loan that I have taken from the 401K, do I pay taxes on the money that I used to repay the loan, or is it pretaxed?
The loan gets paid back with funds from your personal bank account. The funds then grow tax-deferred while in the solo 401k, but taxes are paid once distributed form the solo 401k-usually at retirement.
Interest Rate Deductible QUESTION:
For 401kloan payments, is the interest rate deductible?
No solo 401k loan payments are not tax deductible and payments must be paid with personal funds not business funds.
Interest Rate Deductible For Home Down Payment QUESTION:
Can I deduct the interest on the Solo K loan I made for a home down payment?
No as solo 401k participant loan payments including the interest are not tax deductible even if the proceeds were used toward the purchase of your primary residence. For this reason, participants will borrow form the Roth solo 401k funds instead of borrowing from the solo 401k pretax funds.
Administrator QUESTION:
I understand that me and my wife serve and act as Co-trustees of the solo 401k Trust. Are we also acting in the capacity as the Administrators of the Solo 401K Plan?
Correct that you also the administrator of the solo 401k so you will administer the solo 4o1k participant loan. However, we will provide solo 4o1k participant loan support such as preparing the loan documents, calculating loan amount and payoff amount.
Borrow to pay high interest loan QUESTION:
I want to know if I could borrow (with interest) from my solo 4o1k account, to pay off a high interest real estate loan on an investment property I own in my name.
Yes as pursuant to the solo 4o1k participant loan regulations, the solo 401k participant can use the solo 401k loan proceeds any way he or she wishes.
Making Payments with Stock QUESTION:
I have a couple questions about solo 401k loan payments. Is there a prepayment penalty? Can I transfer stocks to the account and that constitute loan payments? Let me know when you get a chance.
Good questions. No there is no prepayment penalty. However, the loan has to be paid back with after-tax funds not with stocks.
Defer Payments QUESTION:
We currently have one loan on our 401k Trust. Can we defer the payments until January of next year? Do I just crunch the numbers for the interest and draw up an agreement?
(Reg. Section 1.72(p)-1, Q&A-9(b))
Solo 401k Loan grace period for late payment
Effective January 1, 2002, Treas.Reg.1.72 (p)-1, Q&A 10, provides for a cure period that allows a loan participant to avoid an immediate deemed distribution following a missed payment. The cure period may not extend beyond the last day of the calendar quarter following the calendar quarter in which the required payment was due.
Borrow Just to Have Cash QUESTION:
I would like to know if I can borrow $50,000 from my 401k without a specific reason, like a house purchase. I have a little more complex reason, the recent purchase of a vehicle and income taxes have left me lower in cash on hand than I like. Can I borrow for a reason like that? Just to have cash on hand.
Borrow from solo 401k LLC QUESTION:
I just found your website and found it to be very interesting. I have a very precise technical question. I am familiar with IRA LLCs and the rules regarding them. But, not so much with the solo 401k rules. I know you cannot borrow more than $50,000 from a 401k. However, what if one forms an LLC and the solo 401k invests in it? Can the LLC loan more than $50,000 to the owner/participant or to a trust owned by the owner/participant?
The same Solo 401(k) loan participant rules apply regardless if the Solo 401(k) is invested in a single-member LLC whereby the Solo 401(k) is the sole member.
Loan Pay Off Notification QUESTION:
I wasn't certain if I needed to notify you in regards to paying off my 401k participant loan? Do you need anything from me regarding the loan?
With a solo 401k you are the trustee of the plan which means you are the one responsible for documenting the final loan pay off which entails reviewing the loan payment schedule to make sure all payments were made timely, and ending with notating on the memo section of the final check or wire directive that this is a "loan payoff" amount.
Loan Paperwork Shared with IRS QUESTION:
Do I understand correctly that the solo 401k loan paperwork you provide and that I execute is designed to evidence that this is a legitimate loan versus a taxable distribution? Will I have to share this paperwork with the IRS in the normal course of filing or how will I denote on next-year's return that this was not a taxable distribution?
The loan must be confirmed by a legally enforceable agreement (Treas. Reg. 1.72(p)-1, Q&A 3(b). According to regulations, the loan agreement must clearly identify an amount borrowed, a loan term, and a repayment schedule. The solo 401k participant loan would need to be presented to the IRS in the event of an IRS inquiry.