


While over the years many advisors have converted their clients existing self-employed individual 401k/solo 401k from TD Ameritrade to a self-directed solo 401k with our firm, so far this year we have seen a large spike in the number of advisers inquiring and/or using My Solo 401k Financial to restate their clients existing individual 401k/solo 401k from TD Ameritrade.
What is more, effective December 1, 2022 TD Ameritrade will no longer the Roth 401(k) feature in their Individual 401(k) plans resulting in TD Ameritrade’s existing Individual 401k clients being required to restate their plan to a third-party solo 401k plan provider such as My Solo 401k Financial LLC.
As a result, we have put together the following information to help those including advisors impacted by the Schwab TD Ameritrade Merger in transitioning their clients existing TD Ameritrade solo 401k plan to a self-directed solo 401k.
Click on the following link for VIDEO SLIDES
Beat the Upcoming TD Ameritrade Solo 401k Restatement Schwab Merger December 2022 Deadline
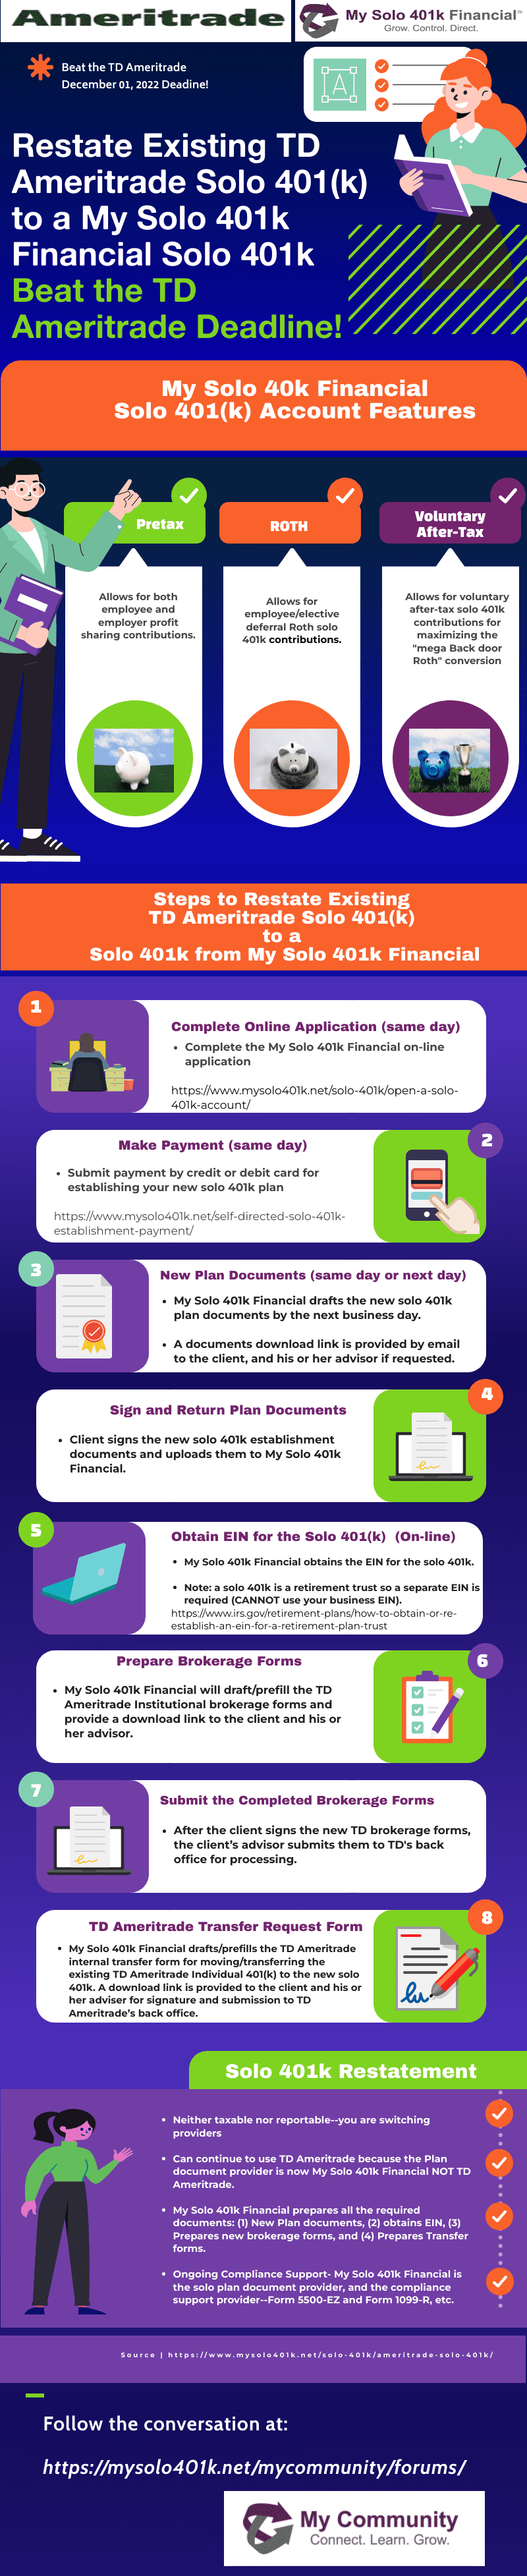
The Steps Involved in Restating Your Existing Individual 401(k) with TD Ameritrade to a Self-Directed Solo 401k with My Solo 401k Financial LLC
Step 1: Online Application: Complete the My Solo 401k Financial on-line application HERE.
Step 2: Make Payment: Submit payment for your new self-directed solo 401k HERE.
Step 3: New Plan Documents: My Solo 401k Financial drafts the new solo 401k plan documents by the next business day and e-mails the document download link by the next business day to the client and his or her advisor.
Step 4: Sign & Return Plan Documents: Client signs the new solo 401k establishment documents and uploads them to My Solo 401k Financial.
Step 5: Obtain EIN: My Solo 401k Financial obtains the EIN for the solo 401k.
Step 6: Prepare Institution Brokerage Forms: My Solo 401k Financial will draft/prefill the TD Ameritrade Institutional brokerage forms and provide a download link to the client and his or her advisor. Note that you also have the option to use Charles Schwab Institutional instead of TD Ameritrade Institutional for the new solo 401k brokerage accounts (e.g., pretax, Roth and Voluntary After-Tax).
Step 7: Submit the Completed Institutional Brokerage Forms: After the client signs the new TD or Schwab brokerage forms, the client’s advisor submits them to TD or Schwab’s back office for processing.
Step 8: TD Ameritrade Transfer Request Form: My Solo 41k Financial drafts/prefills the TD Ameritrade internal transfer form for moving/transferring the existing TD Ameritrade Individual 401(k) to the new solo 401k. A download link is provided to the client and his or her adviser for signature and submission to TD Ameritrade’s back office.
Process as a Restatement
When an existing individual 401k/solo 401k is moved from one plan provider to another, this is known as a restatement.
Neither Taxable nor Reportable
A restatement is not considered a reportable event which means neither a final Form 55000-ez nor a Form 1099-R is issued since the the self-employed business is not terminating the retirement plan but rather changing plan providers.
Can Still Continue to Use TD Ameritrade Institutional
A self-directed solo 401k from My Solo 401k Financial allows the business owner to use TD Institutional for the new solo 401k brokerage accounts. My Solo 401k Financial will even prepare the new TD Institutional brokerage forms at no additional cost.
Here is How a Restatement is Processed
- New Solo 401k Plan Documents
- List the original plan effective date
- Obtain 401K EIN
- Close Existing Account and Open New Account(s)
- Pre-Tax, Roth and Voluntary After-Tax
- Spouses
- TD Ameritrade QRP Distribution Request & Letter of Acceptance
- Not Required: No Final 5500-EZ or 1099-R
Additional Considerations:
- If assets exceed $250K:
- Have you been filing Form 5500-EZ?
- If not, need to file under the IRS Correction Program
- Do you wish to keep investments (in-kind transfer)?
- Confirm that new brokerage account provider offers those funds
- Are there multiple participants (e.g. spouses)?
- Segregate the funds and transfer into separate sub-accounts
- Consider filing an extension to ensure plenty of time to make contributions
Here is What You Retain and/or Gain By Switching to as Self-Directed Solo 401k
- To invest in alternative investments (e.g., real estate, precious metals, Notes, tax liens, cryptocurrency, etc.)
- To gain compliance support with Form 5500-EZ and Form 1099-R preparation.
- To gain access to Solo 401k Loan (borrow from Solo 401k)
- To gain access to making all three contribution types: pretax, Roth, and after-tax
Ongoing Solo 401k Compliance Support
- Form 5500-ez
- If your solo 401k plan balance exceeded $250,000 as of December 31, a Form 5500-EZ is due to the IRS by July 31.
- 1099-R
- Distributions, Rollover, In-Plan Conversions
- Solo 401k IRS Required Plan Updates
- IRS-required plan updates with the next required update occurring in 2022
- Contribution Calculation (including Mega Backdoor Roth)
- Loan Document Preparation
- Alternative Investments
- Account Setup
- Bank, Brokerage, Crypto exchange, etc.




