


Last Updated February 10, 2025
A solo 401k, often referred to by various names such as self-directed Solo 401k plan, self-directed 401k or solo K, allows for various types of contributions as described below.
Contribution Types
- Employer profit sharing contributions
- Pre Tax employee salary deferral contributions
- Roth designated employee contributions
- Employee voluntary after-tax contributions
- Employer Roth profit sharing contributions
Total Contribution Limit

Each contribution type has separate limits, and, when combined, cannot exceed the maximum solo 401k contribution amount which is $69,000 per year or $76,500 for those 50 or older in 2024. For tax year 2025, the maximum contribution that can be made to a solo 401k pan is 70,000 plus $7,500 if you are age 50 or older in 2025. However, if you are age 60, 61, 62 or 63 in 2025 the catch-up contribution increases to $11,250 from $7,500 for tax year 2025.

Solo 401k Contribution Types Explained
Employer profit sharing contributions pre tax or Roth
- Resulting from SECURE 2.0, employer 401k including employer solo 401k contributions can be treated as Roth contributions.
- In accordance with IRC Sec. 404 the profit sharing contribution cannot exceed 25% of income derived from business activity (earned income NOT passive income).
- Salary deferral contributions are not included with profit sharing contributions when calculating the 25 percent deductible contribution.
- If the owner-only business participant has enough net income from self-employment activity, she can treat the entire contribution as a profit sharing contribution which is fully tax deductible on the business tax return if made on a pre tax basis. It is also tax deductible by the business if made as an employer Roth solo 401k contribution, but it will be taxed as an in-plan conversion on the participants personal tax return.
- Note that employee contributions are not part of the employer profit sharing contribution source; therefore, the catch up contribution applicable to those participants age 50 or older cannot be treated as an employer profit sharing contribution.
Example: Janice wants to make profit sharing contributions to her solo 41k for tax year 2024. Janice is age 56, has already made the full employee contribution of $23,000 to her day-time job 401k, and wants to maximize her employer profit sharing contribution to her solo 401k which she set up for her self-employed business. Janice had a good year being self-employed under her S-corporation and received $280,000 in W-2 wages from her self-employed business so she wants to reduce her taxable income for the year by making profit sharing pre tax contributions. Based on $280,000 of W-2 wages from her self-employed business, the maximum profit sharing contribution that Janice may make to her solo 401k for 2024 is $69,000. Because the catch up contribution of $7,500 falls under the employee contribution source not the employer profit sharing contribution source, she cannot make the catch up contribution to her solo 401k plan unless she elects to treat it as an employee contribution which she can technically elect to do since she did not make it to her day time job employer 401k.
- Profit sharing contributions are not required to be made each year.
- SECURE Act 2.0 was signed into law on December 29, 2022 and one of the main changes applies to making Roth employer contributions to 401k plans including solo 401k plans for the self-employed.
Pre Tax employee salary deferral contributions
- Pretax employee salary deferral contributions found under IRC Sec. 402(g) permits business owners to contribute up to 100 percent of compensation not to exceed $23,000 to the solo 401k plan for 2024. The limit increased o $23,500 for tax year 2025.
- The rules also allow for catch-up contributions provided you are age 50 or older. Per IRC Sec. 414 (v), if the business owner has the applicable self-employment earned income, she can make additional catch amounts of $7,500 for 2024 if age 50 or older. The $7,500 employee catchup is the same for 2025. However, if you are age 60, 61, 62 or 63 in 2025 the catch-up contribution increases to $11,250 from $7,500 for tax year 2025.
Roth designated employee contributions
- Since 2006, the self-employed have been allowed to treat all or some portion of their salary deferral limit (the $23,000 in 2024 and $23,500 in 2025) as designated Roth employee solo 401(k) contributions.
- The designated employee Roth solo 401k contributions are outlined in IRC Sec. 402A, and treated as after-tax contributions (that is, you cannot take a tax deduction on your taxes for the contribution).
- The flip side is that all earnings resulting from the employee Roth solo 401k contributions can be distributed tax-free.
- Employee Roth solo 401k annual contributions cannot exceed the $23,000, plus the $7,500 catch-up contribution if age 50 or older for 2024. For 2025, the employee Roth solo 401k contribution is $23,500 plus the $7,500 catch up contribution for those age 50 or older. However, if you are age 60, 61, 62 or 63 in 2025 the catch-up contribution increases to $11,250 from $7,500 for tax year 2025.
Employee voluntary after-tax contributions
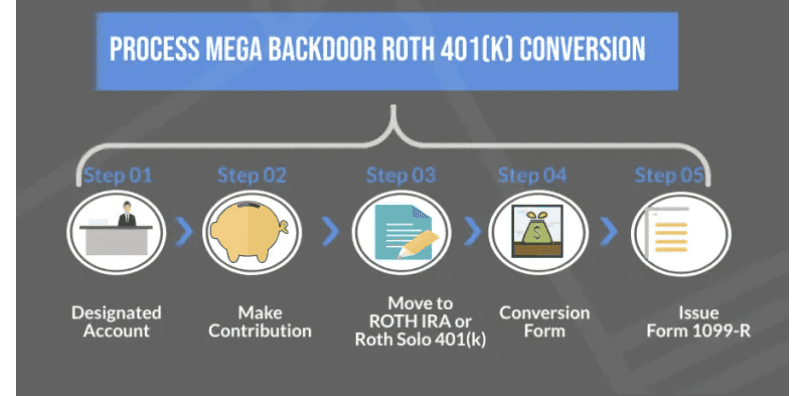
- With the exception of the catch up solo 401k contribution which can be made by those age 50 or older, the solo 401k participant can elect to treat part or all of her solo 401k contributions as voluntary after-tax solo 401k contribution. Therefore, if you have enough earned income from self-employment activity, regardless if you already make contributions to your day-time job 401k plan, 403b or 457 plan, you can contribute the full $69,000 allowable contribution to your voluntary after solo 401k bucket for tax year 2024. For 2025 the limit increased to $70,000.
- Just like employee Roth solo 401k contributions, voluntary after-tax solo contributions are not excluded from income and the owner only business participant cannot deduct them on his or her tax return.
- The voluntary after-tax solo 401k bucket only allows for employee contributions not employer profit sharing contributions.
- Making voluntary after-tax solo 4o1k contributions is a good way to indirectly supercharge your Roth funds whether Roth IRA or Roth 401k funds. Reason being, the voluntary after-tax funds can immediately be converted to a Roth IRA to internally to the Roth solo 401k bucket.
Solo 401k Annual Contribution Tidbits
- All solo 401k contributions cannot be subject to a vesting schedule so are always 100 percent fully vested.
- Rollover contributions are also always vested.
- Provided a triggering event occurs such as age 59 1/2 and no longer being self-employed, Roth solo 401k contributions can be transferred to a Roth IRA or a full-time employer plan such as a Roth 401k, Roth TSP, Roth 457b, and Roth 403b.
- With the passage of SECURE Act 2.0, employer solo 401k contributions can now be applied as Roth employer contributions. https://www.mysolo401k.net/long-awaited-clarity-arrives-irs-releases-secure-act-2-0-employer-roth-401k-including-roth-solo-401k-designated-contribution-reporting-rules-in-notice-2024-2-section-604/
Separate Holding Accounts (Pre Tax, Roth, and Voluntary After-Tax)
While it is considered one solo 401k plan, a solo 401k is a defined contribution plan so separate holding accounts are required for each source of funds- Roth, pre tax and voluntary after-tax solo 401k funds- and for each participant as outlined below.
The requirement for separately tracking the participants’ funds and sources under the plan is satisfied through the use of multiple bank or brokerage accounts.
Example 1: One Participant in the Solo 401k Plan

For example, if the solo 401k plan only has one participant, 1 (one) to 3 (three) separate bank or brokerage accounts may be needed depending on whether or not the participant chooses to make all three contribution types (pretax, roth and voluntary after-tax) or chooses to convert pretax or voluntary after-tax funds to the Roth solo 401k bucket.
For example, if Sarah is the sole participant in her solo 401k plan (the ABC Trust) and she chooses to make all three contribution types, she will need three separate bank or brokerage accounts and they would be titled as follows:
- XYZ Trust (Pretax), Sarah Byrd, Trustee
- XYZ Trust (ROTH), Sarah Byrd, Trustee
- XYZ Trust (After-Tax), Sarah Byrd, Trustee
Example 2: Two Participants in the Solo 401k Plan

If the solo 401k has 2 (two) participants, a total of 6 (six) participant bank or brokerage accounts may be needed if both participants choose to make all three contribution types (pretax, roth and voluntary after-tax).
For example, if Sarah and her spouse Jack both participate in the solo 41k plan and both choose to make all three contribution types, a total of 6 (six) separate bank or brokerage accounts will need to be opened up and titled as follows:
3 Accounts for Jane
- XYZ Trust (Pretax), Jane Do, Trustee
- XYZ Trust (Roth), Jane Do, Trustee
- XYZ Trust (After-Tax), Jane Do, Trustee
3 Accounts for John
- XYZ Trust (Pretax), John Do, Trustee
- XYZ Trust (Roth), John Do, Trustee
- XYZ Trust (After-Tax), John Do, Trustee
The Same Solo 401k Employer Identification Number (EIN)
2024 & 2025 Solo 401k Contribution Guides-Deep Dive
Sole Proprietorship, Independent Contractor, Schedule C, LLC Taxed as Sole Proprietorship, 1099-NEC Independent Contractor
- Slides: Deep Dive 2024 and 2025 Solo 401k Contributions for Sole Proprietor/Schedule C/Contractor/LLC taxed as Sole Proprietorship
- Video: https://www.youtube.com/live/SuI52M1KBio?si=1HWe0netiRchr8ny
- https://www.mysolo401k.net/solo-401k-calculating-solo-401k-contributions-sole-proprietor/
S-corp., C-corp., LLC Taxed as S-corp., W-2
- Slides: S-corporations, C-corporations, LLC taxed as S-corp./C-corp., W2
- Video: https://www.youtube.com/live/nWx-VuzZkwk?si=ol5LnSQTKBtjcjw0
Partnership, LLC Taxed as Partnership (Form 1065-K)
2024 & 2025 Mega Backdoor Roth Solo 401k Guides- Deep Dive
Partnerships, LLC taxed as Partnership
- Slides: Partnerships, LLC taxed as Partnership, Form 1065 Schedule K-1
- Video: https://www.youtube.com/live/YuYqqDs_vUM?si=1Mhg4tRFL6oCp4x_
S-corp., C-corp., LLC taxed as S-corp., W-2
- Slides: Mega Backdoor Roth Solo 401k Deep Dive (S-corp., C-corp., LLC taxed as S-corp, W-2)
- Video: https://www.youtube.com/live/RyoF7regcZM?si=FYC3qIMrnOpHVBgm
Sole Proprietorship, Singe Member LLC or 1099-MISC NECT Contractor
- Slides: 2024-2025 Mega Backdoor Roth Solo 401k Contribution Guide (sole proprietorship, single-member LLC or 1099-MISCNEC Independent Contractor)
- Video: https://www.youtube.com/live/-IzyjNYJbWA?si=vI61AJoEUbAHa6nM
Guides 2023 & 2024-How Much Income Do I need to Max Out Solo 401k Contributions?
S-corp., C-corp., LLC taxed as S-corp., W-2
Sole Proprietorship, Singe Member LLC or 1099-MISC NECT Contractor
Partnerships, LLC taxed as Partnership




